FAQ: How to Stop Living Payday to Payday in Australia – 15 Common Questions Answered
Breaking the payday cycle is one of the most common financial goals for Australians, yet it can feel overwhelming when you're not sure where to start. Whether you're paid weekly, fortnightly, or monthly, the feeling of watching your account drain before your next pay arrives is genuinely stressful — and you're far from alone.
This FAQ article addresses the most common questions Australians ask about escaping the payday-to-payday grind, with practical, honest answers to help you take meaningful steps forward.
The Basics
1. What does "living payday to payday" actually mean?
Living payday to payday means your income is fully consumed by expenses before your next pay cycle arrives, leaving little or no financial buffer. You might cover your bills and essentials, but there's rarely anything left over for savings, unexpected costs, or longer-term goals. It's a cycle that can feel self-reinforcing — one unexpected expense can push you into debt or overdraft, making the next pay period even tighter.
2. Is living payday to payday a budgeting problem or an income problem?
Honestly, it can be either — or both. For some people, income genuinely doesn't cover the cost of living in their area, and no amount of budgeting will fully solve that. For others, income is sufficient but spending patterns haven't been examined closely enough to identify where money is going.
The first step is understanding which situation applies to you. Track your income and every expense for at least four weeks before drawing conclusions. You may find the problem is structural (income too low), behavioural (spending outpacing income), or a combination.
3. How long does it take to stop living payday to payday?
There's no universal timeline, and anyone who gives you a specific number of weeks without knowing your full financial picture is guessing. The honest answer is: it depends on your income, your expenses, your debt levels, and how consistently you can apply changes.
What most people find is that the feeling of the cycle starts to ease once even a small financial buffer exists — even a few hundred dollars set aside can reduce the anxiety of unexpected costs. Getting to a fully stable position, where you're saving regularly and have an adequate emergency fund, typically takes longer and requires sustained effort over months.
Budgeting Questions
4. What percentage of my income should go to bills and essentials?
Common budgeting frameworks suggest allocating a significant portion of take-home pay to needs (housing, utilities, groceries, transport, insurance), a smaller portion to wants, and a portion to savings. One widely referenced approach is the 50/30/20 rule — roughly half to needs, a smaller share to wants, and the remainder to savings and debt repayment.
However, in many Australian cities — particularly Sydney and Melbourne — housing costs alone can consume a much larger share of income than older frameworks anticipated. If your essential costs exceed what traditional rules suggest, that's a signal to look at whether any essential costs can be reduced, whether income can be increased, or both. There's no single percentage that works for everyone.
5. Should I budget weekly, fortnightly, or monthly?
Align your budget period with your pay cycle. If you're paid fortnightly, budget fortnightly. This reduces the mental maths required and makes it easier to track whether you're on track before your next pay arrives.
If you're paid monthly but many of your expenses hit weekly (groceries, fuel), consider breaking your monthly budget into weekly envelopes or sub-categories so you can monitor spending throughout the month rather than discovering a problem at the end.
6. What's the best budgeting method for someone just starting out?
The simplest method you'll actually stick to is the best one. For beginners, a basic approach works well:
- List all income after tax for the period
- List all fixed expenses (rent, loan repayments, subscriptions, insurance)
- Subtract fixed expenses from income to see what's left
- Allocate the remainder across variable essentials (groceries, fuel), savings, and discretionary spending
Many people find that simply writing this down for the first time is revelatory — they've never seen their full financial picture in one place. From there, you can refine your approach as you get more comfortable.
7. How do I budget when my income varies week to week?
Variable income — common for casual workers, freelancers, and those in commission-based roles — makes budgeting harder but not impossible. A practical approach:
- Base your budget on a conservative income estimate — what you can reliably expect in a lower-than-average period, not your best weeks
- In higher-income periods, direct the surplus to savings first before it gets absorbed by spending
- Keep a buffer account that smooths out the variation, so you're drawing a consistent "wage" to yourself even when income fluctuates
The goal is to decouple your spending from the unpredictability of your income.
Savings and Emergency Funds
8. How much should my emergency fund be?
A commonly cited target is three to six months of essential living expenses — enough to cover rent, food, utilities, and transport if your income stopped or a major unexpected cost arose.
For many Australians, this feels like an enormous and distant goal. It's more helpful to think of it in stages:
- Stage 1: A small immediate buffer (enough to cover a typical unexpected expense without going into debt)
- Stage 2: One month of essential expenses
- Stage 3: Three months of essential expenses
- Stage 4: Six months or more, depending on your job security and circumstances
Starting small and building gradually is more achievable than waiting until you can save a large sum all at once.
9. What is the fastest way to build a financial buffer?
Speed depends on how much you can direct toward savings, which comes back to the gap between your income and expenses. That said, some approaches tend to accelerate the process:
- Automate a transfer on payday — even a small amount moved to a separate account before you see it in your main account is less likely to be spent
- Direct any windfalls (tax refunds, bonuses, gifts) straight to your buffer rather than absorbing them into spending
- Reduce one or two significant variable expenses temporarily and redirect the difference to savings
- Sell unused items — a one-time boost that doesn't require ongoing sacrifice
The most important factor is consistency. A small, regular contribution beats a large, irregular one for most people.
10. Should I save money or pay off debt first?
This is one of the most common personal finance dilemmas, and the right answer depends on the type and cost of your debt.
A broadly sensible approach for most people:
- Build a small emergency buffer first (so you don't need to take on more debt when something unexpected happens)
- Pay off high-interest debt (such as credit cards or buy-now-pay-later balances) aggressively, as the interest cost often outweighs what you'd earn in savings
- Once high-interest debt is cleared, split available funds between savings and any remaining lower-interest debt
Carrying high-interest debt while simultaneously trying to save is often counterproductive — the interest accruing on debt is likely higher than any interest earned on savings.
Breaking the Cycle
11. Why do I always seem to spend more when I get paid?
This is a well-documented behavioural pattern. When money arrives, the sense of abundance can temporarily override the discipline you maintained during the lean period before payday. Purchases that felt impossible a few days ago suddenly feel justified.
Some practical ways to counter this:
- Automate savings and bill payments on payday so the "available" balance you see is already reduced
- Wait 24–48 hours before making any non-essential purchase above a threshold you set for yourself
- Review your budget before payday, not just after, so you're reminded of what the incoming money is already allocated to
12. What expenses should I cut first when trying to break the cycle?
Rather than prescribing specific cuts, the most useful approach is to identify your highest-value and lowest-value spending. Look at what you spend on and ask: does this bring me genuine value, or is it a habit I've barely noticed?
Common areas Australians find savings without significant lifestyle impact include:
- Subscriptions that are rarely used
- Convenience spending (takeaway, delivery fees) that's become habitual rather than occasional
- Automatic renewals that haven't been reviewed in some time
Avoid cutting things that genuinely matter to your wellbeing — a budget you resent is a budget you won't maintain.
13. How do I handle irregular expenses that blow my budget?
Irregular expenses — car registration, insurance renewals, school fees, annual subscriptions — are predictable if you plan for them, but they can feel like emergencies if you don't.
The solution is a "sinking fund" approach: identify all the irregular expenses you expect in the next 12 months, add them up, divide by 12 (or by your number of pay periods), and set that amount aside each period into a dedicated account. When the bill arrives, the money is already there.
This transforms irregular expenses from budget-busting surprises into planned, managed costs.
14. What's the difference between a budget and a spending plan?
The terms are often used interchangeably, but some people find "spending plan" more useful psychologically. A budget can feel restrictive — focused on what you can't spend. A spending plan is forward-looking — it's a deliberate decision about where your money goes before it arrives.
Both involve the same mechanics: income, expenses, and allocation. The framing of a spending plan can help shift the mindset from deprivation to intention, which some people find more motivating.
Getting Back on Track
15. What should I do if I've tried budgeting before and it hasn't worked?
First, recognise that most people don't succeed on their first attempt at consistent budgeting — that's normal, not a personal failing. The question is why it didn't work:
- Was the budget unrealistic? A plan that requires perfection will fail. Build in some discretionary spending so the plan has flexibility.
- Was tracking too time-consuming? Simpler systems are more sustainable. You don't need to track every dollar if you automate savings and bill payments first.
- Did unexpected expenses derail it? This points to the need for an emergency buffer before focusing heavily on other goals.
- Was it a solo effort? Sharing financial goals with a trusted person — a partner, friend, or financial professional — can improve accountability.
If you've tried multiple times and continue to struggle, speaking with a financial counsellor can help. Free financial counselling services are available in Australia through the National Debt Helpline and similar organisations.
A Final Word
Breaking the payday-to-payday cycle isn't about being perfect with money — it's about building small, sustainable habits that gradually create breathing room in your finances. The first step is simply understanding where you are right now, and the second is making one small change you can maintain.
No single article can account for your specific circumstances, income, debts, or goals. If your situation is complex, seeking personalised guidance from a qualified financial professional is always worthwhile.
This article is intended as general information only and does not constitute financial advice. Your personal circumstances will affect what strategies are appropriate for you.
Important information
This article is general information only. It does not take your personal circumstances into account and is not personal financial advice. MyBudget is a budgeting and money management service and is not a licensed financial adviser — it does not provide personal advice about investments, superannuation, insurance or financial products. For advice on financial products, speak to a licensed financial adviser.
To talk through your own situation, call MyBudget on 1300 300 922 for a free, confidential, no-obligation appointment.
What is the main topic of the MyBudget article 'Stop Waiting for Payday'?
The article explains how to stop living week to week (payday to payday) by building a realistic budget, an emergency fund, and an automated financial plan, aiming to help readers achieve real financial fitness.
Who wrote the 'Stop Waiting for Payday' article on MyBudget?
The article was written by Cheryl Hayford.
According to the article, why do people end up constantly waiting for payday?
Living payday to payday usually means your money doesn't have a clear plan yet—everyday spending on groceries, food, shopping and subscriptions accumulates, irregular bills catch you off guard, debt repayments stretch the budget, and there's no savings or emergency fund for unexpected expenses, creating a financial treadmill where you run out of money, wait for payday, and reset without getting ahead.
What immediate steps does the article recommend if you're currently in a financial gap before payday?
The recommended immediate steps are: prioritise essentials like rent/mortgage, utilities and food; pause non-essential spending such as subscriptions, takeaways and impulse purchases; check what you already have (pantry items, unused card balances); avoid quick-fix debt traps like pay advance apps and short-term loans; and make extra money before payday through options like selling unused items on eBay, hiring a clothing rack at a preloved store, or side hustles like babysitting or lawn mowing.
What long-term strategy does the article suggest to permanently stop waiting for payday?
The article suggests shifting from reacting to money to planning it in advance through a structured approach: tracking spending to monitor where every dollar goes, paying essentials first by setting up automatic payments for rent/mortgage and bills before discretionary spending, and building a savings buffer or emergency fund.
What key elements does a realistic budget plan need, according to the article, to break the payday-to-payday cycle?
The plan needs to prioritise essential bills, track expenses and spending habits, and set up an automated budget that takes care of bills, savings and debt.
What should you avoid doing when trying to get through to the next payday?
The article advises avoiding quick-fix debt traps such as pay advance apps and short-term loans, since these can make the next payday even tighter.
Images on This Page
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/customer-support.png
Call Desk Profile Picture
-
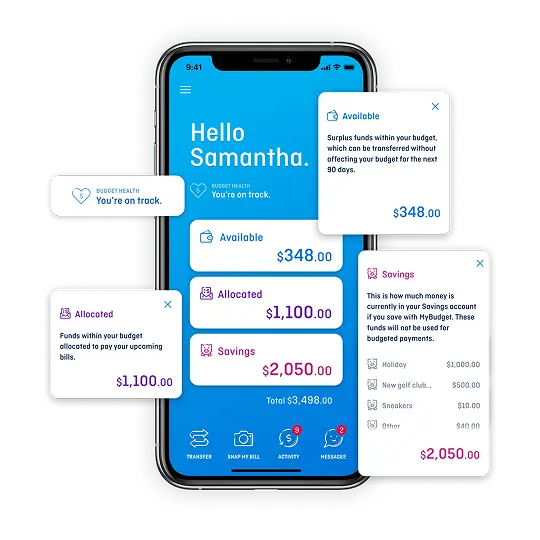
https://www.mybudget.com.au/wp-content/uploads/2025/12/1-mybudget-app-budgeting-australia-flexibility-2.webp
The MyBudget app demonstrating flexible budget planning and debt management features for Australians to reach financial goals.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/adam-erin-couple-client-stories-mybudget-australia.webp
MyBudget clients Adam and Erin, a couple, featured in client stories celebrating achieved financial goals and budget planning success in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/tammy-tips.png
Tammy Barton, Founder and Director of MyBudget, giving her financial tips.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/megan-creagh-client-stories-mybudget-australia-e1764824164539.webp
MyBudget clients Megan and Creagh featured in client stories celebrating achieved financial goals and successful debt solutions in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/tammy-podcast-intro.png
Tammy Barton, Founder and Director of MyBudget, introducing a podcast on budgeting help and achieving financial goals for Australians.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/Michelle-phil-mybudget-clients-australia-transparent-e1765848811345.png
A happy couple, Michelle and Phil, clients of MyBudget Australia, are captured mid-high-five, celebrating their financial success and effective budgeting. The man looks surprised and excited, while the woman is smiling broadly, highlighting the positive results of using MyBudget services to achieve their financial goals in Australia. This image represents the satisfaction and relief of managing personal finances effectively.
-
https://www.mybudget.com.au/wp-content/uploads/2025/03/Erin-MyBudget-client-financially-fit-automated-budget-768x512.png
MyBudget client Erin demonstrating financial fitness after breaking the waiting for payday cycle with a personalised budget plan
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/erin-adam-clients-mybudget-asutralia-bills-success.webp
MyBudget clients Erin and Adam celebrating success after using budget planning for bills and achieving financial goals in Australia.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/personal-budget-template-cta-mybudget-australia.webp
CTA for Australians to download a MyBudget personal budget budget template for effective budget planning and financial goals.
-
https://www.mybudget.com.au/wp-content/uploads/2025/12/adam-erin-family-how-mybudget-works-australia.webp
MyBudget clients Adam and Erin and family demonstrating how the tailored budget planning process works for Australians to achieve financial goals.
-
https://www.mybudget.com.au/wp-content/uploads/2026/01/financial-fitness-erin-money-coach-mybudget-australia.webp
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/mybudget-free-budgeting-tools-calculators-and-resources-australia-1-768x512.webp
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/07/25-best-side-hustles-2026-mybudget-australia-768x512.webp
Illustration of a busy professional juggling multiple tasks, representing 25 of the best side hustles in Australia for earning extra income in 2026.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/healthy-meals-on-budget-guide-resource-mybudget-austalia-715x768.webp
Tablet displaying MyBudget’s Healthy Meals on a Budget Guide for Australian families, created with Accredited Practising Dietitian Samantha Stuk (APD), to help save time and money in the kitchen.
-
https://www.mybudget.com.au/wp-content/uploads/2025/11/call-to-action-image.jpg
Call-to-action image encouraging Australians to seek MyBudget for expert debt solutions and financial coaching.
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/mybudget-trustpilot-australia.webp
Trust Pilot
-
https://www.mybudget.com.au/wp-content/uploads/2025/09/ProductReview-mybudget-reviews-white.png
Product Review
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/Google-mybudget-reviews-white.png
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/mybudget-app-store.png
(no alt text)
-
https://www.mybudget.com.au/wp-content/uploads/2025/10/my-budget-google-play.png
(no alt text)