Rentvesting Explained: Lifestyle, Investment Costs and Finance Trade-Offs
Rentvesting means renting the home you live in while owning a separate investment property. The October 2025 Natloans article presents it as a way to separate lifestyle location from an affordable purchase. Its claims about record prices and growing popularity describe the source’s market narrative, not independently verified current statistics or a forecast of growth.
This article explains what rentvesting is, why it appeals to so many Australians, its genuine advantages and drawbacks, and how to approach it with the right guidance.
What Is Rentvesting?
Rentvesting combines two actions that are usually considered opposites: renting your home and owning an investment property at the same time.
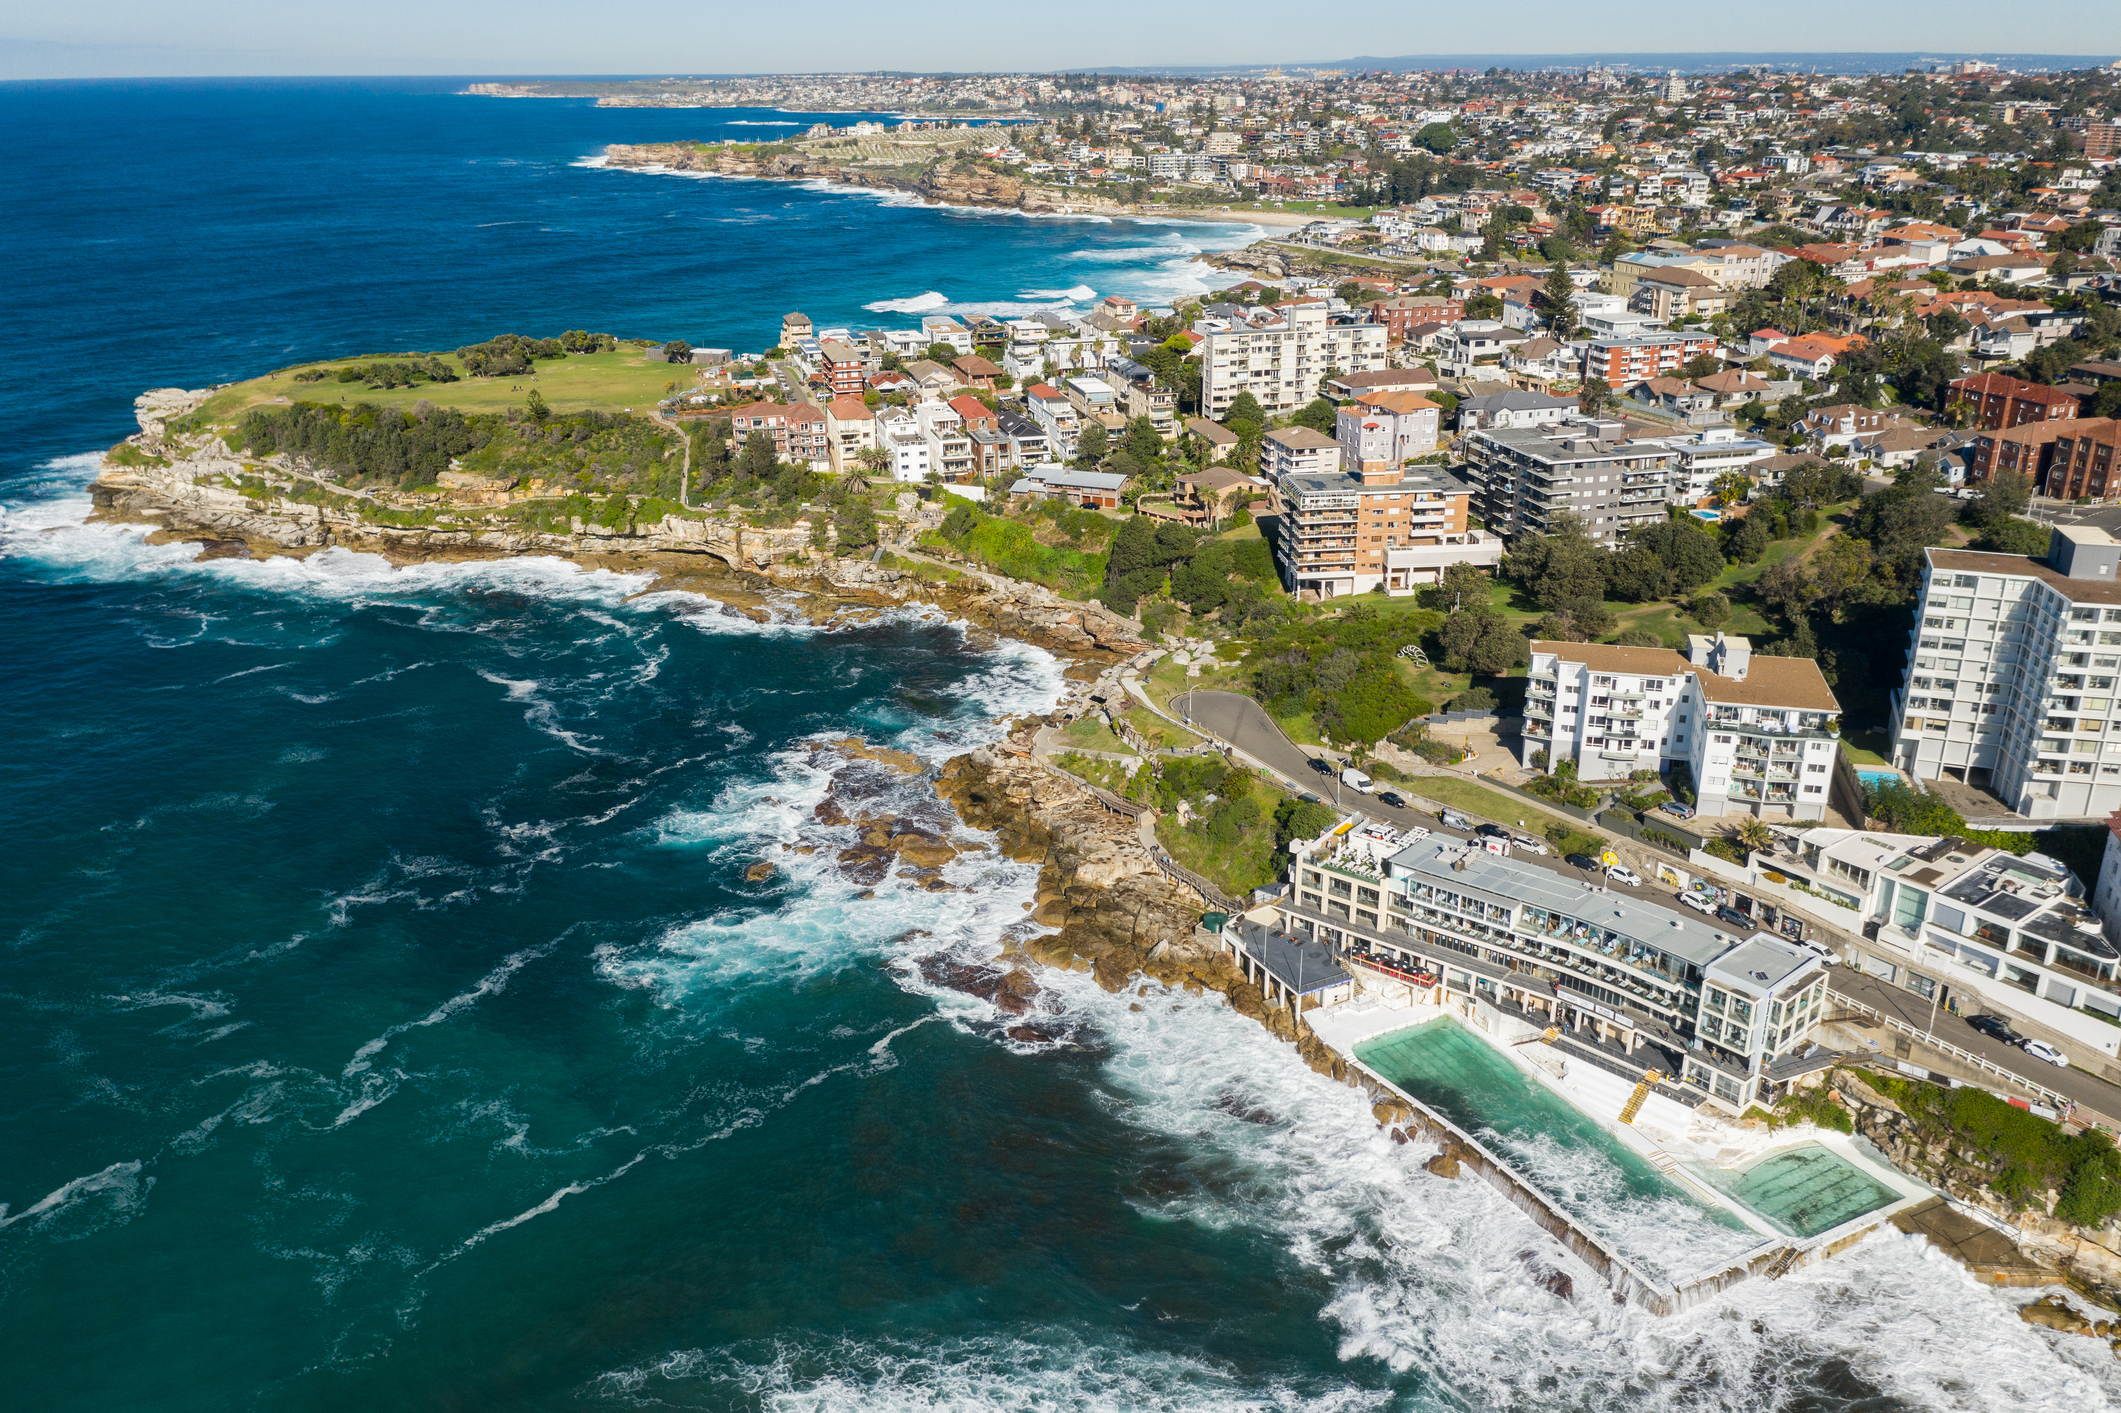
The source illustrates renting a townhouse in Bondi or Fitzroy while buying an investment unit in Brisbane or regional Victoria. These are examples, not location recommendations or evidence of strong future growth or yields. The investment can be in a different area, but a cheaper or high-performing property is not part of the definition or guaranteed.
The core logic is straightforward:
- You rent where you want to live, maintaining the lifestyle and location that matter to you.
- You invest where you can afford, choosing a property based on financial merit rather than personal preference.
The article was authored by Mary Nebotakis, Managing Director of Natloans (B. Eco, Dip. Financial Services), and published on 16 October 2025.
Why Are More Australians Choosing to Rentvest?
The 2025 article links the strategy’s appeal to affordability and lifestyle pressures, particularly for first-home buyers and young professionals. No population or transaction dataset is supplied to establish how many Australians rentvest or whether its popularity is increasing. Its five reasons below are potential attractions rather than assured outcomes.
Several factors are driving this trend:
| Driver | What It Means in Practice |
|---|---|
| Affordability | May allow a lower-priced purchase elsewhere, subject to deposit, costs and finance approval |
| Lifestyle | You can keep living close to work, family, or the beach without being tied to an expensive mortgage in that area. |
| Investment growth potential | Purchasing in an area with strong rental yields and capital growth can build long-term wealth. |
| Tax considerations | Investment properties may offer tax deductions for interest, depreciation, and maintenance. (Confirm your specific position with a qualified accountant.) |
| Flexibility | Separates your residence from the investment location; tenancy terms and ownership costs still apply |
Is Rentvesting Right for You?
Rentvesting is not a universal solution. The Natloans article identifies the following groups for whom it tends to work well:
- First-time buyers priced out of their desired suburbs
- Professionals prioritising lifestyle and location
- Investors wanting to start small and scale their property journey
- People who want property market exposure without sacrificing lifestyle
Whether it suits your situation depends on your goals, financial position, and long-term plan. A mortgage broker and accountant can help you assess this before committing.
Pros and Cons of Rentvesting
Benefits
- Possible earlier entry: a lower-priced investment may be within reach sooner, but price rises and future affordability are uncertain. Compare waiting, buying a home and other uses of savings without assuming urgency guarantees a better outcome.
- Live where you love: Enjoy the lifestyle, commute, or community you prefer, without purchasing a home you cannot afford in that area.
- Build wealth through investment: Your investment property can grow in value and generate rental income over time.
- Potential tax advantages: Investment loan interest and property expenses may be tax deductible, which can improve cash flow. Confirm the specifics with a qualified tax adviser.
- Separate living and investment decisions: owning one investment property does not itself create a diversified portfolio. Concentration in a property, region and tenant can remain a material risk.
Drawbacks to Consider
As identified in the Natloans article (published 16 October 2025), the key drawbacks are:
- You are still paying rent: While your investment property may be earning income, you will need to budget for rent on your own residence.
- Limited grants for investors: First-home buyer grants and stamp duty concessions typically apply to owner-occupiers, not investors. Confirm current eligibility conditions with the relevant state authority and your broker, as these rules can change.
- Ongoing landlord responsibilities: Being a landlord means managing maintenance, tenants, and ongoing financial planning.
- Capital gains tax (CGT): If your investment property grows in value, you may face a CGT liability when you sell. Speak with a qualified accountant about your position.
- Financing complexity: Loan structures for investment properties can differ from standard home loans and may require a more strategic approach.
How to Get Started with Rentvesting: Key Steps
The Natloans article outlines the following planning steps for anyone considering rentvesting:
- Set clear goals. Decide whether rentvesting is a stepping stone toward owning your dream home or part of a longer-term investment plan.
- Know your borrowing capacity. Speak with a mortgage broker to get pre-approved and understand what you can realistically afford. Pre-qualification does not constitute final loan approval.
- Research investment areas. Look for suburbs with strong rental yields, infrastructure growth, low vacancy rates, and potential for capital growth.
- Crunch the numbers. Factor in rental income, mortgage repayments, property management fees, maintenance costs, and tax implications.
- Get expert advice. Work with both a mortgage broker and an accountant to build a strategy suited to your financial situation.
- Have an exit strategy. Consider your long-term plan: will you sell and upgrade, keep the property as a rental, or use the equity to purchase again?
The Role of a Mortgage Broker in Rentvesting
Rentvesting involves more complexity than a standard home purchase. Investment loan structures, tax considerations, and portfolio planning all require careful coordination. A mortgage broker who understands both home loans and investment lending can make a significant difference to the outcome.
According to the Natloans article, the Natloans team works with rentvesting clients to:
- Assess individual goals and financial situations
- Find competitive investment loan options
- Help structure loans for tax efficiency and flexibility
- Coordinate with accountants or financial advisers to build a strategic plan
- Provide support from pre-approval through to property settlement
- Review loans over time, unlock equity, and plan for future purchases
Natloans describes its approach as 100% client-focused, with ongoing support beyond the initial transaction.
Frequently Asked Questions
What exactly is rentvesting?
You rent your own residence and own a separate property as an investment. The owned property need not be in a cheaper area, and rental income or capital growth is not assured. The source’s city examples illustrate the arrangement rather than recommend purchases.
Why are more Australians choosing to rentvest in 2025?
The source attributes its appeal to affordability, lifestyle, possible investment returns, potential tax treatment and flexibility. It supplies no verified adoption figures, so the title’s “more Australians” is a historical claim, not a confirmed trend measured here.
What are the main costs and responsibilities involved in rentvesting?
As identified in the Natloans article (published 16 October 2025), rentvesters need to budget for rent on their own residence while carrying the costs of an investment property. Ongoing responsibilities include maintenance, tenant management, and financial planning. There is also potential capital gains tax exposure on sale, and investment loan structures can be more complex than standard home loans.
Can I still access first-home buyer grants if I rentvest?
The Natloans article notes that first-home buyer grants and stamp duty concessions typically apply to owner-occupiers, not investors. This means rentvesting may affect your eligibility for some government assistance. Grant and concession conditions vary by state and can change — confirm current eligibility with the relevant state authority and your mortgage broker before making decisions.
Are there tax benefits to rentvesting?
Investment properties may offer tax deductions for items such as loan interest, depreciation, and maintenance. Whether these apply to your specific situation depends on your individual circumstances. Always confirm the tax implications of rentvesting with a qualified accountant.
What should I look for when choosing an investment property for rentvesting?
The Natloans article suggests looking for suburbs with strong rental yields, infrastructure growth, low vacancy rates, and potential for capital growth. Thorough research and professional advice are recommended before purchasing.
Do I need a different type of loan for an investment property?
Tell the lender the property will be an investment. Investment purpose can change product pricing, assessment and conditions; it does not mean every borrower needs a wholly different loan structure. Do not describe a rental property as owner-occupied to obtain a product or benefit.
Who is rentvesting best suited to?
According to the Natloans article, rentvesting tends to work well for first-time buyers priced out of their preferred suburbs, professionals prioritising lifestyle and location, investors wanting to start small and scale, and people seeking property market exposure without sacrificing lifestyle. It is not the right fit for everyone, and individual circumstances should be assessed carefully.
What is an exit strategy in rentvesting, and why does it matter?
An exit strategy is your long-term plan for the investment property — for example, selling it to fund a home purchase, retaining it as a rental, or using accumulated equity to buy again. Having a clear exit strategy from the outset helps ensure your rentvesting approach aligns with your broader financial goals.
How can Natloans help with rentvesting?
Natloans offers mortgage broking services for both home loans and investment lending. The team can assess your goals, identify competitive loan options, help structure your loan, and coordinate with your accountant or financial adviser. Support continues beyond settlement, including loan reviews and equity planning for future purchases.
Next Steps
If rentvesting sounds like a strategy worth exploring, the most important first step is to get a clear picture of your borrowing capacity and financial position before researching properties.
Natloans can help you work through the loan structuring questions, connect with the right professionals, and build a plan suited to your goals. To start a conversation, visit the Natloans website and contact the team directly.
You may also find the following related Natloans articles useful:
Source References
- Natloans, What is Rentvesting? The Smart Property Strategy More Aussies Are Using in 2025, authored by Mary Nebotakis (Managing Director, B. Eco, Dip. Financial Services), published 16 October 2025. Retrieved 15 October 2026. https://www.natloans.com.au/what-is-rentvesting-the-smart-property-strategy-more-aussies-are-using-in-2025/
Rates, tax rules, grant eligibility, and lending conditions referenced in this article are not independently verified as current. Confirm all figures and eligibility requirements with Natloans and a qualified accountant or financial adviser before making any financial decisions.
Cash flow and evidence to check before committing
Budget both your own rent and the investment: repayments, rates, insurance, management, maintenance, vacancy, strata charges where relevant, purchase costs and eventual selling costs. Stress-test a period without a tenant, a major repair, higher interest and rising rent on your own home. A lower purchase price or tax deduction does not establish positive cash flow. Property values can fall and selling may take time; borrowing against future equity requires a fresh lender assessment.
The ATO rental-property guidance distinguishes rental income reporting, deductions and record-keeping. Its interest guidance links deductibility to use of borrowed funds for rental income and requires private-use apportionment. Its rental-expense guide separates immediate expenses from capital items, which may have different treatment. Depreciation and maintenance are not blanket deductions for every cost. Have a tax adviser check the transaction, year and any applicable changes; this is not a complete current-year tax ruling or a promise of savings.
The source mentions owner-occupier conditions for first-home assistance. Check the specific grant, concession or guarantee scheme before buying an investment: the purchase may affect later eligibility too. Do not assume all programs have identical ownership or occupation tests.
Natloans’ stated role includes comparing finance, coordinating with the accountant or adviser, assisting through pre-approval and settlement, and later loan reviews. This does not establish unlimited lender coverage, a tax-advice engagement, guaranteed equity access or a review timetable. Confirm scope, costs and responsibilities. Primary ATO guidance was checked on 15 October 2026; the original remains dated 16 October 2025.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/04/image-17-150x150.png
Picture of By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
-
https://www.natloans.com.au/wp-content/uploads/2025/10/iStock-1154283390.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)