Summer Leisure Finance | Boats, Motorcycles, Jet Skis and Purchase Preparation — Natloans
Planning a boat, motorcycle or jet ski purchase means budgeting for the asset, its operation and any borrowing. Natloans’ summer guide discusses secured and unsecured finance, private sales, insurance and preparation before shopping. A seasonal deadline does not establish that borrowing is affordable or that approval will arrive in time.
Original author: Mary Nebotakis, Managing Director, B. Eco, Dip. Financial Services. Published 2 December 2025; captured 15 October 2026. No modification date is supplied in the saved source. Its summer and Christmas framing is dated marketing context, not a verified current demand forecast or funding deadline.
Why buyers consider recreational finance
The source names five uses: first-time boat or motorcycle purchases, upgrades, private-seller purchases, accessories and safety equipment, and new or used assets. Finance can spread the initial purchase into repayments, but interest, fees and ownership costs remain. Payments are not necessarily fixed or monthly; the actual contract sets rate type, frequency and any final balance.
The original describes a growing choice of lenders and competitive leisure products. No market study is supplied to verify that evolution or that current options are affordable for a given household. Compare saving, a lower-cost purchase or deferring it as well as borrowing. Finance does not itself provide purchase protection or certify the asset.
Secured versus unsecured funding
| Issue | Secured | Unsecured |
|---|---|---|
| Security | An agreed asset secures the debt and may be at risk on default. | No specified asset pledged, but debt and recovery obligations remain. |
| Rate and amount | The source suggests potentially lower rates and larger limits; verify the actual offer. | The source suggests potentially higher rates; no current price difference is established. |
| Term | A longer term may lower instalments but increase total interest under otherwise equal assumptions. | Term and repayment flexibility depend on the product. |
| Asset fit | The source suggests newer assets; age, condition and seller still require assessment. | May be considered for older models, smaller items or private purchases not accepted as security. |
| Speed | No guaranteed time to approval or settlement. | Not automatically faster because no asset is pledged. |
Neither structure is universally preferred or cheapest. Newness does not guarantee resale value. Compare the complete quote, security exposure, cash flow, term, fees and any final balance.
Boat purchase: define the complete package
The original covers fishing tinnies, runabouts, cabin cruisers and jet-powered watercraft. It asks buyers to consider the amount to borrow, security, new versus used pricing and additional costs such as a trailer, safety gear and marine accessories. Identify exactly which hull, engine, trailer and equipment are included and what requires separate purchase.
The source claims many lenders provide pre-approval within 24–48 hours. No current lender service commitment is verified, and pre-approval does not confirm an unconditional budget. Ask what information, conditions and expiry apply. Some lenders may require comprehensive insurance; confirm the actual product requirement and timing.
Motorcycle purchase: include riding costs
The original names commuter bikes, cruisers, sports models and adventure bikes for commuters, weekend riders and first-time buyers. It suggests checking security, term and repayment flexibility, riding gear or luggage, and insurance. A prepared application may avoid missing-document queries but does not guarantee a fast decision.
Budget separately for suitable protective equipment, registration, servicing and other running costs. Confirm licence and learner restrictions for the rider and actual bike. Finance approval is not permission to ride a particular model.
Jet skis and personal watercraft
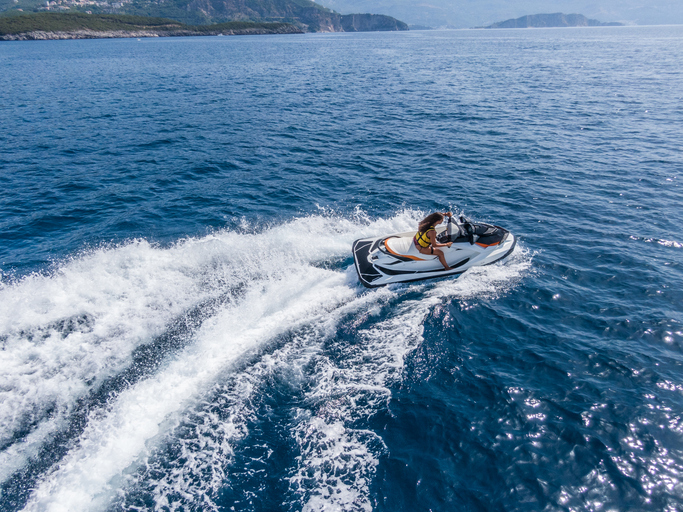
The source describes new and pre-owned PWCs, trailers and safety accessories. Its key questions concern age and condition assessment, conditional pre-approval, dealer versus private purchase, and interest and fees. Claims of growing popularity, low price and peak-season urgency are not verified market findings here.
Check what is included in the package, storage and transport arrangements, insurance, permitted use and the relevant marine authority’s operator, registration and safety requirements. Neither financing a PWC nor obtaining insurance supplies a marine licence or authorises every operating area.
Private sales and older models
Natloans identifies Facebook Marketplace, Gumtree and boating or motorcycle forums as places buyers may find private listings. More choice or lower asking prices do not prove a better total deal. The original recommends checking the asset and encumbrances, legitimate ownership documents, the seller and secure settlement.
Ask the broker what checks it performs, obtain independent condition advice as appropriate and confirm how any existing security will be discharged. A finance professional can assist but cannot be assumed to guarantee a genuine seller, clear title, roadworthiness or seaworthiness. Verify payment instructions through a reliable channel before paying.
For a boat, the PPSR boat-search guidance explains searches using a HIN or official number and recommends searching immediately before purchase. A boat search does not report stolen or damaged status and does not by itself check every engine or trailer. A road vehicle or trailer requires its relevant identifiers and checks. Search results do not replace inspection.
Insurance: inspect the cover as well as the premium
The source describes comprehensive cover for potential theft, damage, accident and loss. Actual protection depends on the policy, insured use, exclusions, limits and claim conditions; “comprehensive” is not a promise that every event is covered.
- Ask whether insurance is required by the particular lender and when evidence is needed.
- Compare agreed-value and market-value wording, valuation limits and any outstanding-loan gap.
- Check safety equipment, storage, rider/operator and use conditions.
- Compare premium, excess and coverage limits together.
- If the premium is financed, include the extra borrowing and interest in total cost; bundling does not prove value.
Build a realistic summer timeline
- Set an affordable overall budget before committing to a trip or purchase.
- Identify the specific asset, seller, inclusions and required independent checks.
- Confirm documents and likely assessment time with the lender; distinguish an indication from a commitment.
- Read any pre-approval conditions and expiry, then confirm final asset acceptance and approval.
- Arrange required cover, safety and operating requirements, settlement and collection.
- Have a fallback if finance, seller documents or inspection is delayed. Do not rely on a seasonal urgency claim.
The original says pre-approval can support shopping, negotiation, quicker action and avoiding missed opportunities. These are possible benefits of preparation, not a confirmed budget, guaranteed purchase or protection against later conditions.
Example: funding the boat does not fund the whole summer
Assume a fictional package costs $18,000 for the boat, $2,000 for a trailer and $1,000 for initial equipment and insurance: $21,000 total. A $16,000 net loan advance plus $4,000 own funds provides $20,000, leaving $1,000 to resolve before purchase. Fuel, storage and ongoing maintenance are additional. These invented numbers are not standard charges or a finance offer. Verify whether quoted package prices already include the trailer before adding it again.
Direct answers
Does pre-approval guarantee funds within 24–48 hours?
No. That timeframe is an unverified source claim about pre-approval. It does not establish final assessment, settlement or asset handover. Ask the actual lender what remains outstanding.
Can accessories, an older asset or a private purchase be financed?
The source describes these possibilities, but the particular borrower, asset, seller and product need assessment. Confirm all permitted items and net funding in writing.
Does financing protect me when buying privately?
It does not provide automatic purchase protection. Check seller, ownership, security, condition and settlement independently; clarify what the broker actually checks.
Does insurance guarantee the loan will be cleared after a loss?
No. Compare the insured amount, excess and policy terms with the potential loan payout. A claim may be limited or excluded, and any loan shortfall remains a separate issue.
Sources and next steps
Discuss the proposed asset, budget, seller and timing through the Natloans website. The original summer guide is the source for the service descriptions above.
Original related reading: business planning during holiday periods and Help to Buy scheme article. Neither establishes a leisure-loan offer.
Primary references checked 16 October 2026 (Melbourne): PPSR guidance linked above, ASIC Moneysmart personal loans, Safe Transport Victoria marine licensing and registration and Transport Victoria learner and restricted motorcycles. Check the authority for the jurisdiction and intended operation; Victorian references are not nationwide operating permission.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/04/image-17-150x150.png
Picture of By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
-
https://www.natloans.com.au/wp-content/uploads/2025/12/iStock-1343962072.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)