Buying an older home in Hobart: valuations, renovation finance and checks
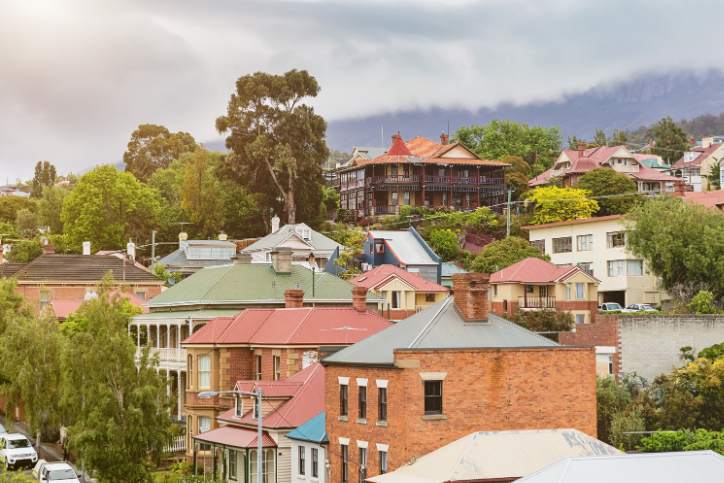
The April 2026 Natloans article highlights Federation homes, weatherboard cottages and post-war brick dwellings in Hobart. It describes their character and potential lending complications; it does not supply a statistical estimate of their share of the market. Property condition and the actual lender’s criteria matter more than age alone.
This article, written by Mary Nebotakis, Managing Director of Natloans (B. Eco, Dip. Financial Services) and published on the Natloans website on 15 April 2026, explains how working with a mortgage broker in Hobart — ideally before making an offer — can help buyers understand what to expect and prepare accordingly.
Why Older Homes in Hobart Can Affect Your Finance
Most buyers expect the finance process to follow a straightforward sequence: find the home, apply for a loan, receive approval, and settle. Older properties can add steps to that process. A lender may request a more detailed valuation, flag concerns about the property's condition, or apply policies that restrict lending on certain construction types or materials.
This does not mean a home loan on an older Hobart property is unavailable. It means buyers can find themselves facing conditions or requirements they hadn't anticipated. The issues tend to cluster around three areas:
- How a valuer assesses the property
- How lenders view current condition and renovation potential
- Whether the paperwork around the property is complete
Understanding each of these before committing to a purchase puts buyers in a stronger position.
How Valuers Assess Older Homes — and What That Means for Your Loan
For the lender’s security assessment, the lender arranges or accepts a valuation under its own requirements. That is distinct from any valuation a buyer obtains independently. The lender’s assessed value can differ from the agreed purchase price.
A valuation at or above the purchase price does not itself guarantee approval or uninterrupted processing. Other lending requirements still apply. A value below the price—a short valuation—may change the available loan amount or funds the buyer needs.
Older homes can be harder to value. There may be fewer comparable sales in the immediate area, or the property may have features that don't fit neatly into standard assessment frameworks. Condition also plays a part: a property requiring significant work may receive a more conservative valuation, even where the buyer intends to renovate.
What to Do if a Valuation Comes in Low
A short valuation is not necessarily the end of a purchase. Several options are available, depending on the circumstances:
- Negotiate the purchase price with the seller
- Cover the gap between the valuation and purchase price with additional savings
- Request a review of the valuation through the lender (possible in some cases, though the outcome is not guaranteed)
- Consider whether not proceeding is legally available and financially appropriate. Ask your solicitor or conveyancer about the actual contract, conditions and deadlines before assuming you can withdraw.
A mortgage broker can help weigh which path fits a buyer's situation. They can also advise whether a different lender might approach the same property differently, since lender policies and valuation instructions vary across the market.
Renovation Plans and What Lenders Generally Consider
For a standard purchase, do not assume a lender will advance against the value of uncompleted renovations. The original’s statement that lenders assess only the current property is too broad for construction finance: CommBank’s published construction process includes an “as if complete” valuation. Confirm the valuation basis for the specific product and approved works. Primary lender example, checked 15 October 2026.
| Renovation Scale | Typical Loan Structure | How Funds Are Accessed |
|---|---|---|
| Minor cosmetic work (painting, flooring, fixtures) | Purchase loan, with a separately planned cosmetic-work budget | Own savings, or available redraw subject to loan terms; a purchase loan does not automatically fund extra works |
| Larger structural projects | Construction or renovation loan | Funds released in stages, tied to progress inspections |
Having this conversation early — before signing a contract — can prevent delays once an application is underway. Knowing which loan structure suits the scale of your renovation means the right product can be identified from the outset.
What to Check Before You Apply
Some preparation specific to older homes can reduce the risk of an application stalling mid-process. The following areas are worth addressing before committing to a purchase.
Building and Pest Inspection
Ask a qualified inspector about the scope of a building and pest report and obtain advice on structural or timber-pest concerns. Such a report is not automatically a specialist asbestos survey. The Australian Government advises that homes built before 1990 may contain asbestos and that visual appearance alone is insufficient. Use a competent asbestos professional where identification is needed. Government home guidance; residential asbestos survey guidance.
Permits for Previous Renovation Work
If the property has been renovated previously, it is worth establishing whether the relevant permits were obtained at the time. Unpermitted work can create complications in valuations and in insurance arrangements.
Strata and Body Corporate Documentation
For properties that are part of a body corporate — some apartment buildings and a small number of older subdivided homes — strata documentation is also part of the picture. Lenders sometimes request body corporate records to check the financial health of the scheme and whether any major works are planned or outstanding. This is not unusual; it is simply more thorough than what is typically required for a newer property purchase.
How a Mortgage Broker in Hobart Can Help
The loan process for an older property has more moving parts than a straightforward new-build purchase. This is not a reason to avoid older homes, but it does mean preparation counts.
A mortgage broker in Hobart who understands how lenders approach Tasmanian properties can provide a clearer view of what to expect before a buyer commits. Specifically, a broker can:
- Match your situation to lenders whose policies are better suited to the property type
- Flag potential issues before they become delays in the application
- Advise on loan structure where renovation plans are involved
- Manage the application on your behalf once you are ready to proceed
Natloans works with buyers purchasing older homes in Hobart and across Tasmania. If you would like to talk through your plans or get a clearer picture of how lenders may view a property you are considering, speak to a mortgage broker in Hobart before taking further steps.
To explore what different loan amounts would look like in repayments, the home loan repayment calculator allows you to adjust loan size, rate, and term to see how repayments shift. Any figures produced are illustrative examples only and depend on the assumptions entered.
Key Considerations at a Glance
| Area | Why It Matters for Older Homes | What to Do |
|---|---|---|
| Valuation | Fewer comparables; condition may reduce assessed value | Understand short-valuation options before you bid |
| Construction materials | Asbestos and certain materials can trigger lender conditions | Obtain building inspection; discuss with broker before applying |
| Renovation plans | Valuation basis depends on the loan and approved works; a construction product may use a completed-value assessment. | Identify correct loan structure before signing a contract |
| Permits for prior work | Unpermitted work can affect valuation and insurance | Request permit history from the vendor or council |
| Body corporate records | Lenders may request financial health and works schedule | Obtain strata documentation as part of due diligence |
| Lender selection | Policies on older property types vary across lenders | Use a broker to match property type to suitable lenders |
Frequently Asked Questions
Do lenders treat older homes differently from newer properties?
They can. As stated in the Natloans article published 15 April 2026, lenders sometimes apply different conditions to older homes — particularly around construction type, property condition, or materials such as asbestos. The policies vary by lender, which is one reason comparing options across a lender panel can be useful before deciding where to apply. (Source)
Can I use a standard home loan to fund renovations after I buy?
For minor cosmetic work, many buyers use savings or a redraw facility on their existing loan. For larger structural renovations, a construction or renovation loan is usually more appropriate, with funds released in stages. A mortgage broker can help determine which structure suits your plans before you apply. (Source)
What happens if the bank's valuation is lower than my purchase price?
A short valuation does not automatically stop a purchase, but it does require a decision. Options include negotiating the purchase price with the vendor, covering the gap with additional savings, or requesting a valuation review through the lender. A broker can help you understand what is realistic given your situation and the property involved.
Does a building and pest report affect the loan process?
The source says lenders do not usually see the buyer’s report. That does not establish a universal rule or mean findings are irrelevant. Ask the actual lender what reports or disclosures are required; condition issues can affect valuation, lending, insurance or your decision to proceed.
Why might lenders have concerns about asbestos in older homes?
The original focuses on pre-1980s homes, but government guidance uses the broader pre-1990 context. A standard building inspection does not guarantee identification. An asbestos professional can assess suspected materials and advise on their management; do not disturb or sample them yourself. Confirm lender and insurer requirements for the actual property.
What is a construction or renovation loan, and when is it relevant?
A construction or renovation loan is a loan structure designed for larger building or structural renovation projects. Rather than releasing the full loan amount at settlement, funds are released in stages tied to progress inspections. This structure is generally more appropriate than a standard home loan when significant structural work is planned. Confirm the specific requirements with Natloans or your lender.
Can a broker help if a lender declines an application on an older property?
A broker can assess whether a different lender on their panel may approach the same property differently, since policies on older construction types and materials vary. This is one of the practical advantages of working with a broker rather than applying directly to a single lender. Whether an alternative lender is available will depend on the specific circumstances of the property and the application.
Should I speak to a mortgage broker before or after making an offer?
The Natloans article recommends speaking to a mortgage broker before making an offer on an older home. Doing so allows you to understand how lenders are likely to view the property, identify the right loan structure for any renovation plans, and avoid surprises mid-application.
What strata documents might a lender request for an older apartment or subdivided home?
For properties within a body corporate, lenders sometimes request body corporate records to assess the financial health of the scheme and check whether any major works are planned or outstanding. Obtaining strata documentation as part of your due diligence before applying can help avoid delays.
Does unpermitted renovation work affect a home loan application?
It can. Unpermitted work may create complications in the lender's valuation and can also affect insurance arrangements. If a property has been previously renovated, it is worth trying to establish whether the relevant permits were obtained at the time, either through the vendor or the relevant council.
Next Steps
If you are considering purchasing an older home in Hobart or elsewhere in Tasmania, the following steps are worth taking before you proceed:
- Speak to a mortgage broker before making an offer, to understand how lenders are likely to view the property type and condition.
- Arrange appropriately scoped building and pest inspections, and specialist asbestos assessment if needed; do not assume one general report covers every issue.
- Clarify the permit history of any prior renovation work with the vendor or local council.
- If the property is part of a body corporate, obtain strata documentation as part of your due diligence.
- Discuss your renovation plans with a broker to identify the right loan structure before signing a contract.
- Use the home loan repayment calculator to explore illustrative repayment scenarios based on different loan sizes and terms.
To speak with Natloans about purchasing an older home in Hobart, contact a mortgage broker before taking further steps.
Related Reading
- Checking Finance Options in Hobart Before You Rule Yourself Out
- Secure More, Stress Less: Smart Finance Moves in Australia's 2026 Economy
- Construction and Renovation Loans — Natloans
- Home Loan Repayment Calculator — Natloans
Source: Natloans public website article by Mary Nebotakis, Managing Director, published 15 April 2026. Retrieved 15 October 2026. Rates, lender policies, grant eligibility and tax rules are not independently verified as current and must be confirmed with Natloans or the relevant lender before making any financial decision.
Before committing to an older-home purchase
Ask your solicitor or conveyancer about contract conditions and deadlines before signing or relying on a right to renegotiate or withdraw. A low valuation does not itself create such a right. Confirm the deposit, loan-to-value basis, other purchase costs and available funds with the lender; the extra cash required is not necessarily just the dollar difference between price and valuation.
Redraw depends on available funds and loan conditions. Construction payments, inspections and evidence requirements vary by lender and contract. A broker can compare lending options but cannot guarantee the property’s condition, insurability, valuation or approval. The primary-source corrections above supplement the preserved April 2026 article; they are not new Natloans internal policies.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/04/image-17-150x150.png
Picture of By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
-
https://www.natloans.com.au/wp-content/uploads/2026/04/How-a-Mortgage-Broker-in-Hobart-Can-Help-You-Buy-an-Older-Home.jpg
Residential hillside neighbourhood with older-style houses and red roofs among green trees, with a misty mountain range in the background under a cloudy sky.
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)