Expanded Home Guarantee Scheme: October 2025 changes and current context
This is a reviewed explanation of Mary Nebotakis’ Natloans article published 27 August 2025 and modified 16 September 2025, which discussed bringing the expanded Home Guarantee Scheme forward to 1 October 2025 from the planned January 2026 start. That launch is now historical. The current name is Australian Government 5% Deposit Scheme; the government-source update below was checked on 15 October 2026.
What Is the Home Guarantee Scheme?
The Home Guarantee Scheme is a Federal Government initiative designed to help Australians buy a first home without needing to save the traditional 20% deposit. Under the scheme:
- Eligible first home buyers can purchase a property with as little as a 5% deposit.
- The Government acts as guarantor for up to 15% of the lender-assessed property value.
- Because the government guarantee replaces the need for a full 20% deposit, buyers are not required to pay Lenders Mortgage Insurance (LMI).
Avoiding LMI can represent a significant upfront saving. The article notes this saving could fall in the range of $10,000 to $30,000 or more depending on the purchase price — this is a general illustration from the source, not a guaranteed figure for any individual loan. Confirm the exact cost impact for your circumstances with a broker.
Prior to the expansion announced in 2025, the scheme was subject to income limits, property price thresholds, and a restricted number of places available each financial year.
What Changed from 1 October 2025?
As described in the source article (published 27 August 2025, last modified 16 September 2025), the expanded scheme introduced three major changes:
- Earlier start date — The expansion was brought forward to 1 October 2025, three months ahead of the originally planned date.
- Higher property price caps — Maximum purchase prices were lifted substantially across capital cities and regional areas.
- No income caps — First home buyers with higher incomes became able to access the scheme, broadening eligibility beyond previous income-tested limits.
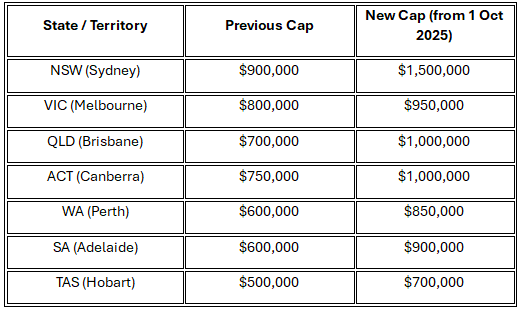
Property Price Cap Comparison (as published August 2025)
The article cited specific examples of how caps changed in major cities. These figures are sourced from the original article and must be confirmed as current before you act on them:
| City / Region | Previous Cap (as published) | New Cap from 1 Oct 2025 (as published) |
|---|---|---|
| Sydney | $900,000 | $1,500,000 |
| Melbourne | $800,000 | $950,000 |
The earlier caps in this table are the original article’s historical comparison. The government information guide dated 1 July 2026 confirms the current capital-city caps of $1.5 million for NSW and $950,000 for Victoria. Both purchase price and lender-assessed property value must fit the relevant cap. Check the specific location with the participating lender; a cap is not the amount you can necessarily borrow.
Why This Matters for First Home Buyers
The article identifies four key implications of the expanded scheme:
More Buying Power
Higher property price caps mean first home buyers can consider properties that were previously outside the scheme's limits, particularly in competitive capital city markets.
Significant Cost Savings
Avoiding LMI removes a substantial upfront cost. The source article notes potential savings in the $10,000–$30,000-plus range as a general illustration; the actual amount depends on the loan size and lender, and should be calculated for your specific situation.
Earlier Opportunity
The original urged preparation because the October 2025 launch preceded the previously planned January 2026 start. This is historical launch context, not a new deadline or a reason to rush a purchase now.
Increased Competition
The article notes that property experts have warned more buyers entering the market simultaneously could create upward pressure on prices, particularly in capital cities. Long-term supply and demand factors will also influence outcomes.
How First Home Buyers Can Prepare
The article sets out four practical steps for buyers considering the scheme:
1. Get Pre-Approved
A pre-approval provides a conditional borrowing indication for planning. It does not guarantee final finance or remove property, valuation or contract risks. Ask the lender which conditions remain and obtain legal advice before committing.
2. Understand Your Property Price Cap
Each city and region has a specific threshold. Knowing the cap for your target area helps you refine your property search and avoid pursuing properties the scheme cannot support.
3. Plan Your Budget Carefully
A 5% deposit means a larger loan balance than a 20% deposit would. The article advises buyers to ensure that repayments fit comfortably within their budget before committing.
4. Seek Expert Guidance
Working with a mortgage broker can help you compare participating lenders, access competitive rates, and navigate the application process correctly.
How to Apply
Applications for the Home Guarantee Scheme must be made through participating lenders. Not all lenders participate, so it is important to identify which lenders are approved under the scheme. A mortgage broker can help identify suitable participating lenders and guide you through the application requirements.
Eligibility — Key Points
Based on the source article as published in August 2025:
- The scheme is primarily designed for first home buyers.
- Depending on the category, it may also apply to single parents and other eligible groups.
- From October 2025, eligibility was described as broader, with fewer restrictions and no income cap.
- Personal eligibility depends on individual circumstances and should be confirmed with a broker or the relevant government authority before you apply.
Deposit Example (from source)
The article provides the following illustrative example to show how the 5% deposit requirement works in practice:
Example only, based on source article assumptions: For a property purchase price of $700,000, a 5% deposit equals $35,000. A standard 20% deposit on the same property would be $140,000. This example is for illustration only and does not account for other purchase costs such as stamp duty, legal fees or lender charges.
Frequently Asked Questions
What does this Natloans article discuss?
The article discusses the expanded Home Guarantee Scheme as described at the time of publication (27 August 2025). It covers what the scheme is, what changed from 1 October 2025, how first home buyers can prepare, and how to apply. It is general information in that dated context and should be read as such. Read the original article at Natloans.
Is this article a current quote or eligibility assessment?
No. The source was published on 27 August 2025 and last modified 16 September 2025. It is general information in that dated context. Costs, conditions, property price caps and eligibility requirements should be confirmed for your current circumstances before you rely on any figure or condition mentioned. Source: Natloans article.
What is the Home Guarantee Scheme?
The Home Guarantee Scheme is a Federal Government program that helps eligible buyers purchase a property with as little as a 5% deposit. The Government guarantees up to 15% of the lender-assessed property value, meaning buyers can avoid paying Lenders Mortgage Insurance (LMI).
Who is eligible for the expanded scheme?
As described in the August 2025 source article, the scheme is primarily for first home buyers, with eligibility from October 2025 described as broader and without income caps. Other categories such as single parents may also be eligible depending on the scheme category. Personal eligibility depends on individual circumstances — a Natloans broker can help confirm whether you qualify.
How much deposit do I need?
For eligible first buyers, the scheme requires at least 5% of lender-assessed property value; eligible single parents or legal guardians may use the separate 2% pathway. The source’s $700,000 example gives $35,000 at 5% versus $140,000 at 20%, assuming value equals price. Budget for other purchase costs and ask about any valuation gap.
Do I still have to pay LMI under the scheme?
No. The Government guarantee replaces the requirement for LMI, which is one of the scheme's primary benefits for buyers who cannot save a full 20% deposit.
How do the new property price caps help first home buyers?
The expanded caps allow buyers to use the scheme on higher-value properties. As published in August 2025, the Sydney cap rose from $900,000 to $1.5 million, and Melbourne's cap rose from $800,000 to $950,000. Caps for other cities and regions also increased. Confirm the applicable cap for your area before you begin your property search.
Could the scheme push property prices up?
The original predicts that more participants could increase competition and place upward pressure on some prices. It also recognises broader supply and demand factors. This is a forecast attributed to unnamed experts, not verified evidence of a price effect or a reason to waive conditions or buy quickly.
How do I apply for the Home Guarantee Scheme?
Applications must be made through participating lenders. Working with a mortgage broker such as Natloans can help you identify the right lenders, access competitive rates, and receive guidance through the application process.
Does a pre-approval guarantee my loan will be approved?
No. A pre-approval is an indicative assessment of your borrowing capacity based on information provided at that point in time. It is subject to full lender assessment and does not constitute a formal loan approval.
Where can I get help understanding whether the scheme suits my situation?
Natloans brokers can help you assess your eligibility, understand the property price caps in your target area, compare participating lenders, and structure your finance. Contact Natloans to speak with an experienced mortgage broker.
Next Steps
If you are a first home buyer considering the Home Guarantee Scheme, the article recommends taking action early. Key steps are:
- Contact a Natloans broker to discuss your eligibility and borrowing capacity.
- Confirm the property price cap that applies to your target city or region.
- Obtain a pre-approval so you are ready to act when the right property becomes available.
- Review your budget to ensure loan repayments are manageable at the loan size a 5% deposit implies.
Contact Natloans to speak with an experienced mortgage broker and explore your options.
Source References
- Primary source: Expanded Home Guarantee Scheme Brought Forward to 1 October 2025 — Natloans. Published 27 August 2025; last modified 16 September 2025. Retrieved 15 October 2026. Author: Mary Nebotakis, Managing Director, Natloans.
- Related reading: Car Finance Options Explained: Personal, Business & Refinancing Solutions — Natloans
- Related reading: Spring Clean Your Finances: 3 Quick Wins for a Fresh Financial Start — Natloans
This enriched explanation preserves the source’s launch story, cap comparison, deposit example, planning steps and related links. Current checks and corrections are editorial additions, not new statements authored by Mary. Source byline: Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services. The original claim that Natloans has helped thousands of first buyers is a publisher claim, not an independently verified client count.
Current government-source clarification
The scheme overview confirms the new name, no income caps and the 5% first-buyer or 2% eligible single-parent/legal-guardian paths. The official FAQ says eligible places are unlimited; property caps, occupancy, applicant eligibility and lender approval still apply. Returning owners may qualify under the specified ownership-history rules.
The government information guide specifies a first-buyer guarantee limit up to 15% of property value, correcting the article’s description of 15% of the loan. The guarantee protects the lender; it is not money paid to you and does not remove your repayment obligations.
A higher scheme price cap expands the set of potentially eligible properties; it does not automatically increase a borrower’s approved budget. Ask which participating lenders Natloans can access and compare fees, rates and features. Broker involvement does not ensure approval or the lowest rate.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/04/image-17-150x150.png
Picture of By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
-
https://www.natloans.com.au/wp-content/uploads/2025/08/table.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/08/expanded-home-guarantee-scheme-brought-forward-to-1-october-2025-what-first-home-buyers-need-to-know.jpg
Expanded Home Guarantee Scheme Brought Forward to 1 October 2025: What First Home Buyers Need to Know
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)