Car Loans | Compare Vehicle Finance, Costs and Ownership — Natloans
Natloans is an Australian finance and mortgage brokerage arranging vehicle finance for personal and business needs. Its public page covers new and used cars, first cars, upgrades and refinancing through bank and non-bank lenders. It claims access to more than 50 lenders across the brokerage; this does not establish how many offer each vehicle product or accept a particular application.
The captured page has conflicting starting rates: its title says from 6.49% p.a., while its body says from 6.99% p.a. with a comparison rate of 7.63% p.a. These figures were observed on 15 October 2026 and are not verified as current. The extract does not give comparison-rate assumptions; the 5 August 2026 modification date does not establish the offer’s effective date. Obtain a written quote for the actual loan.
Rates, fees, and eligibility conditions vary by product, lender, and individual circumstances. Nothing on this page constitutes a rate guarantee or credit approval.
Why Choose Natloans for Your Car Loan?
The following credentials are stated on the Natloans website (retrieved 15 October 2026) and should be confirmed with Natloans for current accuracy:
- Multi award-winning team with expertise across all types of lending
- More than 10,000 customers across Australia, with an excellent Google rating
- More than 100 years of combined financial services experience across the team
- More than 15 years in business helping Australians with their finance needs
- Access to over 50 of Australia's leading banks and non-bank lenders
Because Natloans works across a broad lender panel rather than representing a single institution, brokers can compare commercial and consumer options side by side and present solutions tailored to your budget, vehicle type, and intended use.
Car Finance Products Available Through Natloans
Natloans lists ten distinct vehicle finance products. Each links to a dedicated page with further detail. The right product depends on factors including whether the vehicle is for personal or business use, your employment and income type, your credit history, and the vehicle itself. Speak with a Natloans broker to determine which structure suits your situation.
| Product | Typical Use | More Information |
|---|---|---|
| Personal Car Loans | Private individuals purchasing a vehicle for personal use | Personal Car Loans |
| Business Car Loans | Business owners financing a vehicle for business purposes | Business Car Loans |
| Chattel Mortgage | Business use; borrower takes ownership of the vehicle at settlement | Chattel Mortgage |
| Electric Vehicle Loans | Finance tailored for the purchase of electric vehicles | Electric Car Loans |
| Low Doc Car Loans | Borrowers who cannot provide standard income documentation | Low Doc Car Loans |
| Finance Lease | Business use; lender retains ownership; borrower leases the vehicle | Finance Lease |
| Bad Credit Car Loans | Borrowers with impaired or limited credit history | Bad Credit Car Loans |
| Car Loan Refinancing | Replacing an existing car loan with a new arrangement | Car Loan Refinancing |
| Sale and Leaseback | Releasing equity from a vehicle already owned | Sale and Leaseback |
| Novated Car Lease | Employees financing a vehicle through salary packaging with employer involvement | Novated Car Lease |
Personal Car Loans
Personal car loans are designed for individuals purchasing a vehicle primarily for private use. Natloans sources these from its lender panel and structures repayments to suit different budgets. Visit the personal car loans page for product-specific detail.
Business Car Loans
Business car loans are available for sole traders, companies, and other business structures purchasing vehicles for business purposes. Different structures — such as chattel mortgage or finance lease — may suit different businesses depending on accounting treatment, GST registration, and cash-flow preferences. Confirm the most appropriate structure with your accountant and a Natloans broker. Visit the business car loans page for further information.
Chattel Mortgage
A chattel mortgage is business asset finance under which the borrower owns the vehicle subject to the lender’s security. Any balloon, release conditions and tax treatment depend on the agreement and circumstances. GST credits are distinct from income-tax deductions; registration does not guarantee a full credit. See the chattel mortgage page and confirm tax treatment with an accountant.
Finance Lease
Under a finance lease, the lender retains ownership of the vehicle during the lease term and the borrower makes regular lease payments. At the end of the term there is typically a residual or balloon payment. This is generally a business finance product. See the finance lease page for details.
Novated Car Lease
A novated lease combines an employee’s vehicle lease with an employer-supported salary-packaging arrangement. Payments can include pre-tax and post-tax amounts. Employer participation, fees, tax treatment, residual obligations and employment changes all matter; a payroll deduction is not a separate personal tax deduction. See the novated lease guide and check the package with payroll and a tax adviser.
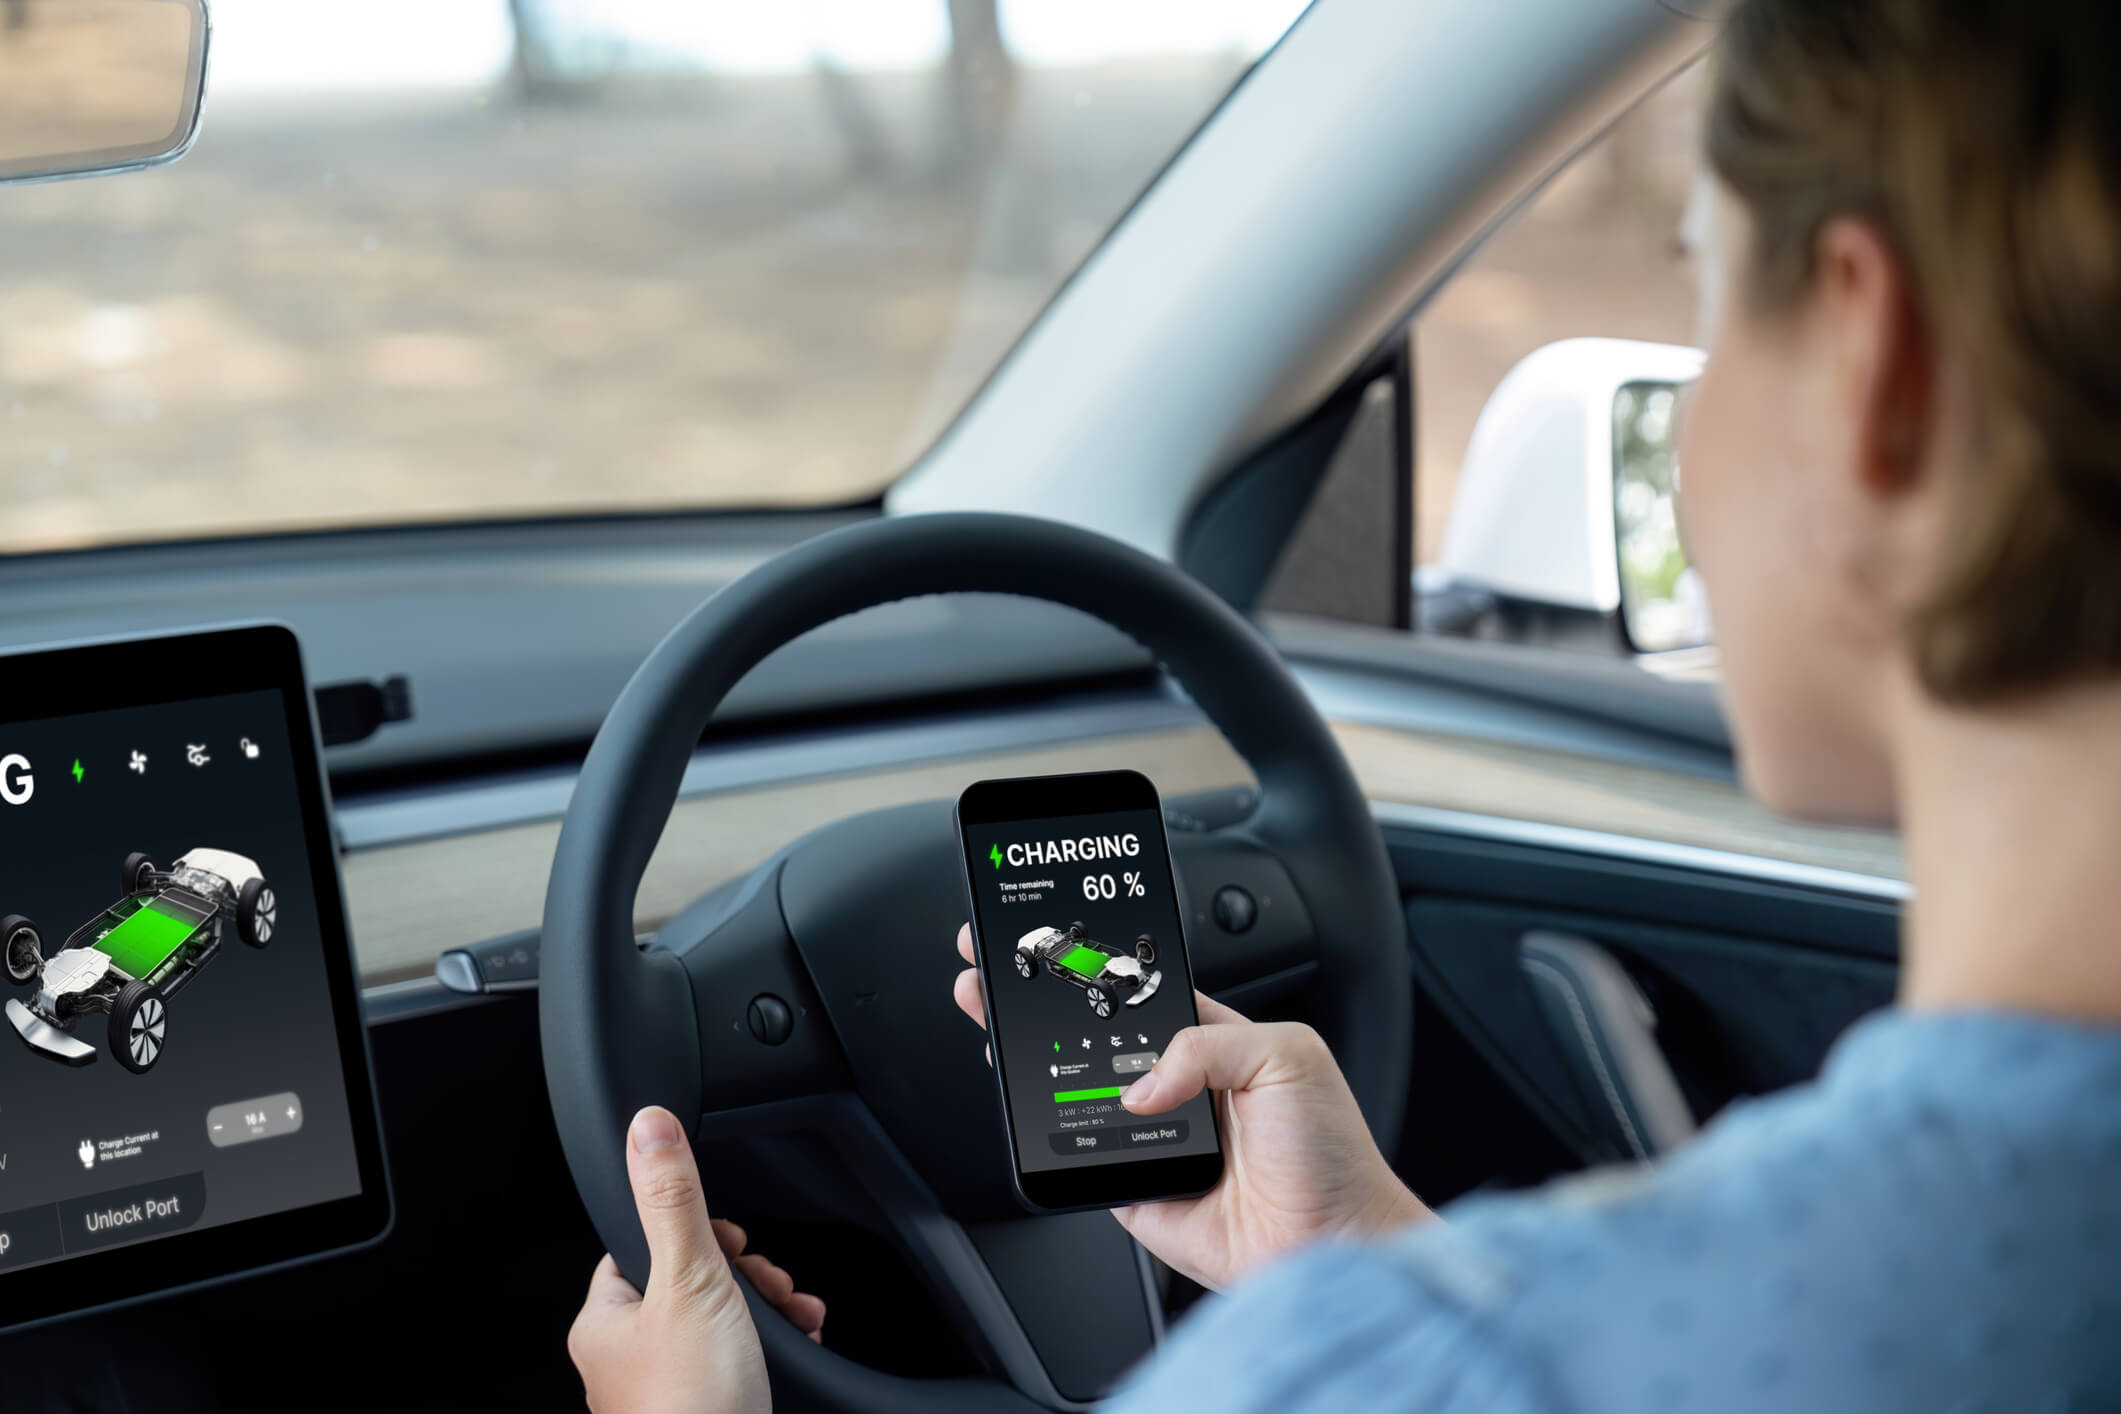
Electric Vehicle Loans
Natloans offers finance specifically for electric vehicles. Applicable government incentives or concessional rates, if any, should be confirmed at the time of application as policies change. See the electric car loans page for current information.
Low Doc Car Loans
Low doc car loans are designed for borrowers — often self-employed individuals — who may not be able to provide the standard income documentation required by mainstream lenders. Alternative documentation requirements and applicable rates should be confirmed directly with Natloans. See the low doc car loans page.
Bad Credit Car Loans
Natloans lists a bad credit car loan option for borrowers with impaired or limited credit history. Approval is not guaranteed and will depend on individual circumstances, the lender's assessment, and the specifics of the application. See the bad credit car loans page for more information.
Car Loan Refinancing
If you already have a car loan, refinancing may allow you to move to a different rate or loan structure. Whether refinancing is beneficial depends on your current loan terms, any exit fees, and the terms of a new loan. Natloans can help you compare options. See the car loan refinancing page.
Sale and Leaseback
Sale and leaseback allows a borrower who already owns a vehicle to sell it to a financier and lease it back, releasing equity while retaining use of the vehicle. Suitability depends on individual and business circumstances. See the sale and leaseback page.
What to Expect from a Natloans Car Loan
The following features are described on the Natloans car loans page (retrieved 15 October 2026). Specific terms, conditions, and availability should be confirmed with Natloans before applying.
- Competitive rates: Natloans aims to compare suitable offers across its panel. The source’s more-than-50-lender claim is not a guarantee that every applicant accesses every lender or receives the lowest rate in the market.
- Flexible loan options: Products are available for personal, business, and specialist needs, with structures that can be tailored to budget and intended vehicle use.
- Streamlined process: The application process is described as fast, with brokers aiming to move from initial enquiry to approval efficiently.
- Expert guidance: Natloans brokers guide applicants through product selection, documentation, and lender requirements throughout the process.
- Repayment calculator: The original page advertises weekly, fortnightly and monthly estimates. This mirror has no working calculator. Use the original page for its advertised tool and confirm the actual loan’s schedule, fees and final amount.
How the Car Loan Process Works
Natloans describes a three-step process on its car loans page. Pre-qualification does not constitute final credit approval.
- Step 1 — Pre-Qualify: Answer a few initial questions about your circumstances and vehicle requirements. This helps Natloans understand your needs before searching the lender panel. Start a quick quote.
- Step 2 — Compare and Select: Natloans presents loan options from relevant lenders side by side. Review the rates, fees, loan term, repayments, and any residual or balloon payments before selecting a product.
- Step 3 — Get Approved: The lender assesses the full application and may impose conditions. After approval, complete the required documents and settlement steps before collecting the vehicle. Approval is not automatic funding or delivery.
To discuss your situation before starting, you can also speak to the Natloans team directly.
Choosing the Right Car Finance Structure
Several factors influence which car finance product is most appropriate for your situation:
- Purpose of use: Personal use generally suits a consumer car loan; business use may suit a chattel mortgage, finance lease, or business car loan depending on your structure and accounting preferences.
- Employment and income: Payslips, tax or business records help establish income. Having payslips does not itself qualify someone for a loan, and self-employment does not automatically require low-doc finance. Confirm the evidence the selected lender accepts.
- Credit history: A strong credit history typically provides access to a wider range of lenders and lower rates. Borrowers with impaired history may be directed to specialist lenders.
- Vehicle type: New, used, and electric vehicles may be treated differently by lenders. Age and condition of the vehicle can affect eligibility and rate.
- Ownership preference: Some products (chattel mortgage, secured personal loan) result in the borrower owning the vehicle from settlement; others (finance lease, novated lease) involve the lender or a third party retaining ownership during the term.
- Residual or balloon: Identify any final amount and plan how to meet it. It is not a guaranteed resale value, and refinancing requires approval. Lease return or purchase conditions differ from paying off a loan.
- Tax and GST considerations: Business finance structures may have different GST and tax deductibility implications. Always confirm these with a qualified accountant before selecting a product.
Natloans brokers can help you work through these factors. Use the quick quote tool to begin, or contact the team to discuss your options.
Natloans' Lender Panel
The captured page claims access to more than 50 banks and non-bank lenders across Natloans’ lending services and separately labels commercial and consumer car lenders. This is not evidence that all 50 offer car loans or are available to every borrower. Confirm the relevant panel and the lenders actually compared for the application.
What Customers Say
The captured Natloans widget displayed “Excellent” based on 925 reviews and labelled the reviews as Google-sourced through Trustindex. Its badge text described a score above 4.5 over the prior 12 months. These are widget claims observed on 15 October 2026, not an independent review-count or authenticity audit. The following are paraphrases of public customer accounts, not independently verified transaction records or guaranteed service levels; no private client records are joined to them.
-
Hayley Patterson, 8 October 2026 (Google, via Trustindex): Hayley described her broker Lizzy as helpful and the process as streamlined and easy to follow. She noted the turnaround from first contact to finance payout was very quick, and that Lizzy kept her consistently informed and responded promptly to questions.
-
Laura Ferlazzo, 6 October 2026 (Google, via Trustindex): Laura described broker Declan as knowledgeable, responsive, and efficient, and said the process was straightforward. She indicated she would recommend Natloans.
-
Yoganand Ramphul, 1 October 2026 (Google, via Trustindex): Yoganand described Natloans as an amazing broker and noted this was his fifth loan with them. He said the team always provides good advice and the right products for individual needs.
-
Kimberlyn Wise, 30 September 2026 (Google, via Trustindex): Kimberlyn credited broker Lizzy Lawrence with securing a low-interest car loan, noting great communication and prompt responses to queries.
-
Erika Rupping, 29 September 2026 (Google, via Trustindex): Erika said they had used Natloans for loan applications for over five years and found the team professional, helpful and easy to work with. She praised listening and attention to their circumstances. Her review does not establish whether the loans were business or personal.
-
Scott Quilliam, 23 September 2026 (Google, via Trustindex): Scott praised broker Michelle as warm, professional, and detail-oriented, describing the process as easy and well communicated.
-
Shining Bee Cleaners, 11 September 2026 (Google, via Trustindex): The reviewer praised Jonathan Dhondee for communication, service and rapid delivery, and said they were looking forward to driving their “merc” that weekend. This is the reviewer’s public account, not independent verification of a completed purchase.
-
Junior Crichton, 11 September 2026 (Google, via Trustindex): Junior described broker Jonathan as thorough, prompt, and attentive to detail. He noted Jonathan explained every step clearly and said he would reach out to Jonathan again and recommend him to others.
-
Janice Kerr, 11 September 2026 (Google, via Trustindex): Janice described her experience with broker Michelle Douthie as wonderful, noting Michelle was patient and more than helpful.
-
Saief Subakat Chowdhury, 6 September 2026 (Google, via Trustindex): Saief said he requested a quote on 21 August at 10:11am and received a call from Michelle about 20 minutes later. He described guidance and a deal from Alex Bank which he preferred to other quotes, and said the dealer received funds on 25 August. These details belong to this public review, not a promised response or funding timeline for other car finance applications.
Read more Natloans reviews on Trustindex
Frequently Asked Questions
Which car finance options does Natloans offer?
Natloans lists ten vehicle finance products: personal car loans, business car loans, chattel mortgage, electric vehicle loans, low doc car loans, finance lease, bad credit car loans, car loan refinancing, sale and leaseback, and novated car lease. Each product has a dedicated page with further detail. Source: natloans.com.au/car-loans.
What is the advertised starting rate for a Natloans car loan?
The title captured on 15 October 2026 says from 6.49% p.a.; the body says from 6.99% p.a. and a 7.63% p.a. comparison rate. None is a verified current offer. Ask Natloans to reconcile the figures and provide the rate, assumptions, fees and total payable for your loan.
How do I compare car finance options through Natloans?
Use the relevant product pages and the repayment calculator on the Natloans website to explore options, then discuss your vehicle, purpose, budget, and circumstances with a Natloans broker. When you receive a loan offer, compare the actual interest rate, comparison rate, fees, loan term, and any residual or final payment before deciding. Source: natloans.com.au/car-loans.
Can I apply for a car loan if I am self-employed or have limited documentation?
Natloans lists a low doc car loan product for borrowers who cannot provide standard income documentation. Eligibility and the documentation required will depend on the lender's criteria. Confirm requirements with Natloans. See the low doc car loans page.
Can I apply for a car loan if I have bad credit?
Natloans lists a bad credit car loan option for borrowers with impaired or limited credit history. Approval is not guaranteed and depends on individual circumstances and the lender's assessment. See the bad credit car loans page for more detail.
Is there a finance option for electric vehicles?
Yes. Natloans lists electric vehicle loans as a dedicated product. See the electric car loans page. Any applicable government incentives or policy concessions should be confirmed at the time of application, as these change.
What is the difference between a chattel mortgage and a finance lease?
Under a chattel mortgage, the borrower takes ownership of the vehicle at settlement while the lender holds a security interest over it. Under a finance lease, the lender retains ownership during the term and the borrower makes lease payments, typically with a residual amount at the end. Both are generally business finance products. The most appropriate structure depends on your business type, GST registration, and accounting preferences — confirm with your accountant and a Natloans broker.
What is a novated lease?
A novated lease involves the employee, employer and financier. Salary packaging can include pre-tax deductions and post-tax contributions; employer agreement and individual tax treatment matter. Compare total after-tax cost, running-cost budgets and the residual, and do not assume automatic transfer to another employer. See the novated lease page.
Can I refinance an existing car loan through Natloans?
Yes. Natloans offers car loan refinancing. Whether refinancing is beneficial depends on your current loan terms, any break or exit fees, and the terms of a new loan. Discuss your existing loan details with a Natloans broker. See the car loan refinancing page.
What is sale and leaseback finance?
Sale and leaseback allows a borrower who already owns a vehicle to sell it to a financier and lease it back, releasing equity while retaining use of the vehicle. Suitability depends on individual and business circumstances. See the sale and leaseback page.
How does the application process work?
Natloans describes a three-step process: pre-qualify by answering initial questions; review loan options presented side by side; then proceed to a full application for lender approval. Pre-qualification is not a guarantee of approval. Start with a quick quote or contact the team to discuss your situation first.
How do I get in touch with Natloans?
You can start a quick quote online at natloans.com.au/quick-quote or contact the team directly via the Natloans contact page.
Next Steps
- Get a quick quote: Start your car loan enquiry online — answer a few initial questions to help Natloans understand your needs.
- Explore products: Review the dedicated pages for each car finance product listed above to understand the features, conditions, and suitability of each option.
- Use the repayment calculator: The Natloans website includes a calculator to estimate weekly, fortnightly, or monthly repayments. Results are estimates only.
- Speak to a broker: Contact the Natloans team via the contact page to discuss your vehicle, purpose, budget, and circumstances before applying.
- Compare your offer carefully: When you receive a loan offer, review the interest rate, comparison rate, fees, loan term, and any residual payment before accepting.
Source References
- Natloans Car Loans page — natloans.com.au/car-loans. Published 20 May 2025; last modified 5 August 2026; retrieved 15 October 2026. Rates and details stated are as of retrieval date and must be confirmed with Natloans before relying on them.
- Trustindex review summary — trustindex.io
Use the product list as a starting point
The ten categories overlap. “Electric” describes a vehicle; “low-doc” describes an evidence pathway; “bad credit” describes a borrower circumstance; and a lease, secured loan or salary-packaging arrangement changes the legal and payment structure. Ask which actual contract is proposed and who owns the vehicle. For business finance, an ABN alone does not turn a private purchase into a business-purpose transaction.
Prepare a car-finance comparison brief
| Question | Information to collect |
|---|---|
| What are you buying? | New/used status, model, age, seller, agreed price, deposit/trade-in and intended use |
| What can you afford? | Income, regular expenses, existing debts and a budget including insurance, registration, fuel or charging, servicing and tyres |
| What is borrowed? | Amount financed, any fees or optional products added to it, and the cash required upfront |
| What will you pay? | Interest basis, comparison-rate assumptions where applicable, payment frequency, term, fees and total scheduled payments |
| What remains at the end? | Balloon/residual, ownership or return conditions, likely sale value and any shortfall plan |
| What if plans change? | Extra-payment rules, early payout, employment changes for salary packaging, and hardship contact details |
This is an editorial preparation checklist, not a lender’s mandatory document list. Use a verified secure application channel for identity, bank and income records. An eligibility check or finance approval is not a mechanical inspection, warranty assessment or confirmation that a particular car is good value.
Compare the complete cost, not just the regular payment
For a hypothetical pair of quotes financing the same amount over 60 months with the same upfront contribution and no other fees, $500 each month plus an additional $10,000 final balloon totals $40,000. A quote with $650 monthly and no balloon totals $39,000. The first has lower regular payments but $1,000 more scheduled payments in total. These are illustrative schedules, not current offers or calculated market interest rates; they exclude vehicle operating costs and any effect of payment timing. Do not add a balloon twice if it is already included in a quoted total.
Refinancing should compare the remaining cost of the existing loan with the full cost of the replacement, including payout and setup fees and any longer term. A lower monthly repayment can result from paying for longer. For sale and leaseback, ownership changes and continued use is subject to lease conditions; cash released after existing debt and costs must be weighed against future rentals.
ASIC’s Moneysmart car-loan guide explains secured borrowing, interest rates, fees and balloon payments. It supports checking the complete commitment rather than relying on a headline rate. Primary guidance checked on 16 October 2026 (Melbourne time). Public Natloans content supplies the service descriptions and historical advertising; no private client file was used.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/05/Car-Loans-Home-Page-1.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/06/natloans-car-loans.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/06/Natloans-Car-Loan-8.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/Personal-Car-Loans.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/Business-Car-Loans.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/Chattel-Mortgage.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/electric-vehicle-loans.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/Low-Doc-Car-Loans.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/Finance-Lease.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Bad-Credit-Car-Loans-.jpg
Car Loan Refinancing
-
https://www.natloans.com.au/wp-content/uploads/2025/04/Car-Loan-Refinancing.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/Sale-and-Leaseback.jpg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/Novated-Car-Lease.jpg
(no alt text)
-
https://cdn.trustindex.io/assets/platform/Google/star/f.svg
Google star 1
-
https://cdn.trustindex.io/assets/platform/Google/logo.svg
Google
-
https://cdn.trustindex.io/assets/platform/Google/icon.svg
Google
-
https://lh3.googleusercontent.com/a/ACg8ocIvHMR8Vl8BxHm1mXzrR9Wl4zixgjnjXkDWaqWYIyCm6nKSJg=w40-h40-c-rp-mo-br100
Hayley Patterson profile picture
-
https://lh3.googleusercontent.com/a/ACg8ocLLGNjYxCCqbbf571N8FJH-m3cL3P_Ka3Ry2BHUV7DG2vXSjA=w40-h40-c-rp-mo-br100
Laura Ferlazzo profile picture
-
https://lh3.googleusercontent.com/a-/ALV-UjWWiiM2KpnJUxpd5vwFZAugTH6LX_hD1FUFgUzjHGX_OBVmnKLSzA=w40-h40-c-rp-mo-br100
Yoganand Ramphul profile picture
-
https://lh3.googleusercontent.com/a-/ALV-UjVZhWcmeQJu19CbHdeUA8yeKBuiP-_Y5g4zRbubzdXyrAJlcaE_Jw=w40-h40-c-rp-mo-ba12-br100
Kimberlyn Wise profile picture
-
https://lh3.googleusercontent.com/a/ACg8ocIvN8TQlLZzeDmsgjkmw-EHgOI6CnYaPZ4erXy1pQvcpXMKwA=w40-h40-c-rp-mo-br100
Erika Rupping profile picture
-
https://lh3.googleusercontent.com/a-/ALV-UjVHvxuRu5jsbyhdn2r4MfIix-j4AMYvDztcuB6T8LiRb28GfbU=w40-h40-c-rp-mo-br100
Scott Quilliam profile picture
-
https://lh3.googleusercontent.com/a-/ALV-UjV5h6t0Mp-xXjaj9H_XbVKXJ49KRjeGxGdSXqFWqRSNsSKaRqM=w40-h40-c-rp-mo-br100
Shining Bee Cleaners profile picture
-
https://lh3.googleusercontent.com/a/ACg8ocK_pwn7z4-6IdCmDcaRiHxvTvPULxPgoHYRx0UECC-pdGNr5Q=w40-h40-c-rp-mo-br100
Junior Crichton profile picture
-
https://lh3.googleusercontent.com/a-/ALV-UjVYSy-gc4vyxH5ruXAobnA1lty7fOhoOXr4uYWGk_dtkwaMs_Io=w40-h40-c-rp-mo-br100
janice kerr profile picture
-
https://lh3.googleusercontent.com/a-/ALV-UjU0UaETa2cvTRq0HE-IdVJaQilnDh3F1eG5XCr_jLjXXG8A574=w40-h40-c-rp-mo-ba12-br100
Saief Subakat Chowdhury profile picture
-
https://www.natloans.com.au/wp-content/uploads/2025/04/awards.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/awards-m.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/australian-motorcycle-and-marine-finance.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/anz.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/angle-finance.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/automotive-financial-services.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/azora.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/banjo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/branded-financial-services.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/capital-finance.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/cba.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/dynamoney.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/earlypay.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/finance-one.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/flexi-commercial.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/judo-bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/secure-funding-liberty.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/metro-finance.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/moneyme.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Moneyme-Autopay-Logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Morris-logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/nab.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/pepper-money.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/plenti.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/resimac.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/selfco.png
selfco
-
https://www.natloans.com.au/wp-content/uploads/2025/04/shift-financial.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/scotpac.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/westpac.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Affordable-Car-Loans-Logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Alex-Bank-Logo-Updated.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Azore-Logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Branded-Financial-Services-Logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/carstart-logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/gamma-duo-logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/firstmac.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/latitude-financial-services.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/Money3-logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/now-finance.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/11/racv-logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/wisr.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)