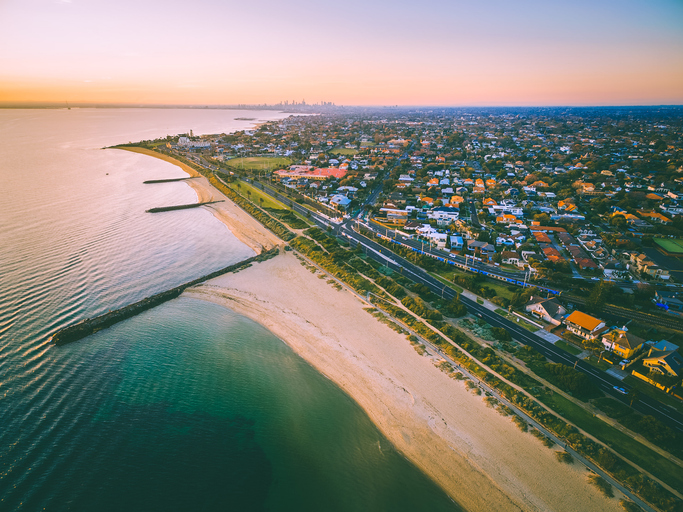
Financing a Sandringham Home Upgrade: Equity, Timing and Loan Options
Changing needs can prompt Sandringham and Bayside homeowners to compare renovating with buying a larger property. The source describes property values as evolving; it does not establish that prices are currently rising or provide a verified local price series. This guide develops its finance considerations for bedrooms, work space, outdoor space and a longer-term family home.
Why Sandringham Homeowners Are Choosing to Upgrade
Natloans’ source describes Sandringham as a desirable coastal location, citing beaches, schools, transport, shopping and community. These are the publisher’s reasons for local appeal, not independently ranked desirability or evidence that every household should stay or upgrade.
According to the Natloans article, common reasons homeowners choose to upgrade include:
- Growing families requiring additional bedrooms
- Increased demand for dedicated work-from-home spaces
- Lifestyle changes and entertaining requirements
- Larger outdoor areas for children and pets
- Moving closer to preferred schools, parks and amenities
- Purchasing a long-term family home
For many Bayside homeowners, upgrading within the same area allows them to remain in a location they value while securing a property that better suits their future plans.
Understanding Your Borrowing Capacity
Before beginning a property search, reviewing your borrowing position is a practical early step. Lenders generally assess a range of factors when determining how much a borrower may be eligible to borrow. These typically include:
- Employment type and income
- Existing loans and financial liabilities
- Household living expenses
- Available savings
- Existing property equity
- Credit history
Borrowing calculations can vary significantly between lenders, which is one reason many homeowners choose to work with a mortgage broker before approaching individual institutions. A broker can compare lending policies across multiple lenders and help establish realistic expectations around budget and purchasing capacity.
Using Home Equity to Support an Upgrade
For homeowners who have owned their property for a number of years, accumulated equity may play an important role in the upgrade process. Home equity generally refers to the difference between a property's current market value and the remaining balance of the mortgage.
Depending on individual circumstances, usable equity may potentially assist with:
- Deposits on a new property
- Stamp duty and other purchasing costs
- Renovation work after settlement
- Reducing the amount of upfront cash required
Property values across Sandringham and neighbouring Bayside suburbs have changed considerably over time. As a result, many homeowners find it worthwhile to review how much usable equity may be available before planning their next move. A mortgage broker can assist with this assessment in the context of current lender requirements.
Selling Before Buying vs Buying Before Selling
Timing is one of the most frequently raised questions for upgrading homeowners. Both approaches carry distinct advantages and considerations.
Selling Before Buying
Selling your existing property first may provide greater certainty around available funds and borrowing requirements. Potential advantages can include:
- A clear understanding of the equity available from the sale
- Reduced exposure to holding two properties simultaneously
- Greater confidence when setting a purchase budget
A potential drawback is that temporary accommodation may sometimes be required if settlement dates do not align neatly.
Buying Before Selling
Purchasing a new property before selling the existing one may allow homeowners to move directly into their next home. However, this approach involves additional considerations, including:
- Managing two properties during the transition period
- Additional borrowing requirements
- Coordinating settlement timeframes across both transactions
- Potential cash-flow implications
The most suitable approach depends on individual circumstances, financial objectives and prevailing market conditions. A mortgage broker can help assess which path may be more appropriate for a given situation.
What Is Bridging Finance?
Bridging finance is a solution commonly explored by homeowners who wish to purchase a new property before their existing home has settled. A bridging loan may provide temporary funding during the transition period, allowing borrowers to secure their next property without waiting for proceeds from the sale of their current home.
Because bridging finance structures can vary between lenders, the Natloans article recommends seeking guidance from a mortgage broker when comparing available options. Factors that may be considered include:
| Factor | What to Consider |
|---|---|
| Loan structure | How the bridging loan is arranged relative to existing and new mortgages |
| Interest costs | How interest accrues during the bridging period |
| Loan term | The maximum period the bridging loan will remain in place |
| Exit strategy | How the bridging loan will be repaid, typically through the sale of the existing property |
| Property values | How lenders assess both properties when calculating the bridging amount |
| Borrowing capacity | Whether the borrower can service the combined debt during the transition |
Specific bridging finance terms, costs and eligibility criteria vary between lenders and should be confirmed directly with Natloans or the relevant lender.
Costs to Budget for When Upgrading
Planning a property upgrade involves budgeting for more than just the purchase price. The Natloans article identifies a range of additional expenses that homeowners should factor into their overall budget:
- Stamp duty
- Conveyancing and legal fees
- Building and pest inspections
- Moving costs
- Loan establishment fees
- Property valuation fees
- Lenders Mortgage Insurance (where applicable)
Understanding these costs early can help provide a clearer picture of the total funds required. A mortgage broker can assist in identifying which costs are likely to apply in a given situation.
Home Loan Structures: Fixed, Variable and Split
When upgrading to a new property, homeowners may also wish to review the structure of their home loan. The Natloans article outlines three common options:
Fixed Rate Loans
Fixed-rate loans lock in a set interest rate for an agreed period, which may provide repayment certainty during that time. This can be useful for budgeting purposes, though conditions and break costs can apply if circumstances change.
Variable Rate Loans
Variable-rate loans move in line with lender rate changes and may offer greater flexibility, including features such as offset accounts and redraw facilities. These features can help reduce interest costs over time, depending on how they are used.
Split Loans
A split loan combines fixed and variable components within the same mortgage. This allows borrowers to balance repayment certainty on one portion with the flexibility of a variable rate on another.
The most appropriate structure depends on individual financial circumstances, risk tolerance and future plans. A mortgage broker can explain how different lenders structure these products and help identify the most suitable option.
Why Work With a Mortgage Broker in Sandringham?
As noted in the Natloans article (published 2 June 2026), upgrading a home often involves multiple moving parts — borrowing assessments, equity calculations, property sales, loan approvals and settlement coordination. Working with a mortgage broker can simplify the process of comparing lenders and navigating finance options. Rather than approaching lenders individually, a broker can compare multiple loan products, interest rates and lending policies from a broad panel of lenders.
For homeowners throughout Sandringham, Brighton, Hampton, Black Rock, Cheltenham, Mentone and the wider Bayside region, local knowledge can also be valuable when planning an upgrade. Familiarity with local market dynamics and the types of properties commonly purchased in these areas may assist in structuring a finance solution that reflects realistic conditions.
How Natloans Assists Bayside Homeowners
Natloans describes itself as having assisted thousands of Australians with finance solutions across home loans, refinancing, personal loans and asset finance. According to the article, Natloans mortgage brokers assist homeowners throughout Sandringham and Melbourne's Bayside suburbs with:
- Borrowing capacity assessments
- Home loan comparisons across a panel of lenders
- Equity release strategies
- Bridging finance options
- Home upgrades and property purchases
- End-to-end application support
The article also states that Natloans provides access to more than 50 lenders, holds over 750 five-star Google reviews (as at the article's publication), draws on more than 15 years of industry experience, and has a team with over 100 years of combined lending expertise. These figures are reported as published in the article dated 2 June 2026 and should be confirmed with Natloans for current accuracy.
Natloans was recognised as the Best Finance Brokerage (Office) for Victoria and Tasmania at the Adviser Better Business Awards 2026, as stated in the article. This award recognition is reported as published and has not been independently verified.
Frequently Asked Questions
What does a mortgage broker in Sandringham actually do when helping someone upgrade their home?
According to the Natloans article (published 2 June 2026), a mortgage broker assists with borrowing capacity assessments, comparing home loan products across multiple lenders, equity release strategies, bridging finance options and end-to-end application support. Rather than approaching individual lenders separately, the broker compares lending policies and loan structures on the borrower's behalf. Source: natloans.com.au
What factors do lenders consider when assessing borrowing capacity for a property upgrade?
The article lists employment and income, existing loans and liabilities, household expenses, available savings, property equity and credit history as factors lenders generally consider. Borrowing calculations can vary between lenders, which is one reason mortgage brokers compare policies across institutions. Source: natloans.com.au
How might existing home equity be used when upgrading a property in Sandringham?
The article suggests equity might support a deposit, purchase costs or later renovations. Total equity means value less outstanding mortgage; usable borrowing is a separate lender assessment. Accessing it through a new loan adds debt rather than turning all equity into free cash. Confirm the lender valuation, maximum lending, serviceability and costs.
Is it better to sell my current home before buying a new one, or buy first?
The article outlines both approaches. Selling first may provide greater certainty around available funds but may require temporary accommodation. Buying first may allow a direct move but involves managing two properties during the transition, additional borrowing and cash-flow considerations. The most suitable approach depends on individual circumstances and market conditions. Source: natloans.com.au
What is bridging finance and when is it typically used?
Bridging finance is a short-term funding solution used by homeowners who wish to purchase a new property before their existing home has sold and settled. A bridging loan may provide temporary funding during this period. Structures, costs and eligibility vary between lenders. The article recommends seeking guidance from a mortgage broker when comparing bridging finance options. Source: natloans.com.au
What additional costs should I budget for beyond the purchase price when upgrading?
The article identifies stamp duty, conveyancing and legal fees, building and pest inspections, moving costs, loan establishment fees, property valuation fees and Lenders Mortgage Insurance (where applicable) as potential additional expenses. Budgeting for these early can help provide a more accurate picture of the total funds required. Source: natloans.com.au
What is the difference between a fixed, variable and split home loan?
Fixed-rate loans offer repayment certainty for an agreed period. Variable-rate loans move with lender rate changes and may include features such as offset accounts and redraw facilities. Split loans combine both components within the one mortgage. The article notes that a mortgage broker can explain how lenders structure these options and help identify the most suitable arrangement for individual circumstances. Source: natloans.com.au
Does Natloans only assist homeowners in Sandringham?
No. The article states that Natloans assists homeowners throughout Sandringham, Brighton, Hampton, Black Rock, Cheltenham, Mentone and the wider Bayside region. Source: natloans.com.au
How many lenders does Natloans compare?
The article states that Natloans provides access to more than 50 lenders, as published on 2 June 2026. This figure should be confirmed with Natloans for current accuracy. Source: natloans.com.au
How should I treat the figures and policy references in this article?
The original article was published on 2 June 2026 and last modified 27 July 2026. Its figures, market commentary and policy references reflect that publication context. Current lender terms, eligibility conditions and any applicable government schemes should be verified with Natloans or the relevant authority before making a decision. Source: natloans.com.au
Related Reading
- Why Cheltenham Homeowners Are Reviewing Their Mortgages in 2026
- A Guide to Buying an Apartment in Brighton
Next Steps
If you are considering upgrading to a larger property in Sandringham or elsewhere in Melbourne's Bayside region, speaking with a mortgage broker may help you better understand your borrowing position and available home loan options. Whether you are exploring equity, comparing lenders, reviewing bridging finance or preparing for your next property purchase, Natloans can assist.
To get started, book a free home loan consultation with Natloans or call 1300 955 791 to speak with an experienced mortgage broker.
This article is based on content published by Natloans on 2 June 2026 (last modified 27 July 2026) and is authored by Mary Nebotakis, Managing Director, Natloans (B. Eco, Dip. Financial Services). It is intended as general information only. All figures, lender counts, award references and market commentary are reported as published at that date and must be confirmed with Natloans or the relevant authority before any financial decision is made. Pre-qualification and borrowing assessments do not constitute final loan approval.
A practical comparison before choosing the sequence
| Scenario | Figures to establish | What could change |
|---|---|---|
| Sell first | Actual sale price less mortgage payout and selling costs, cash remaining, next purchase costs and loan needed | Settlement timing, temporary accommodation, moving twice, and prices while searching |
| Buy first | Required cash and peak debt while holding both properties, interest and fees, conservative sale proceeds and end debt | A slower or lower sale, an extension refused, and additional holding costs |
| Renovate instead | Scope, quotes, approvals, funding costs and contingency, compared with buying and selling costs | Cost overruns, delays and a finished value below expectations |
This comparison expands the source’s decision framework; it is not a Natloans approval checklist. Ask the conveyancer about contractual deadlines and conditions. A lender’s initial estimate or conditional approval does not remove the obligations in a signed purchase contract.
In addition to the source’s seven purchase-cost categories, include selling-agent and marketing costs, mortgage discharge or applicable fixed-rate break costs, and overlapping holding or accommodation costs. LMI depends on the proposed lending and any exemption. Compare fixed-period limits and possible break costs, variable-rate changes and feature fees, and both portions of a split loan.
For bridging, define the temporary facility and any ongoing loan separately. Westpac’s own explanation distinguishes arrangements with and without end debt and explains that capitalised interest can create interest on interest. This is one lender’s explanation, checked 15 October 2026, not a universal offer or evidence that Natloans can arrange that product for every applicant. Obtain the actual facility terms.
The source’s panel, customer-review, experience and award figures remain attributed to Natloans. Its free consultation does not imply fee-free loans, conveyancing or valuations, and a service reference to Sandringham does not establish a staffed office there.
Images on This Page
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-white-logo.webp
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/natloans_logo.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-person.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-money-case.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-money-bag.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_electric-car-rounded.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_edit-document.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/solar_chat-round-money-bold.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/material-symbols_credit-card.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-calculator.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-service.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/icon-bank.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/04/ic_round-home.svg
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-dollar.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-first.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-construction.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-saving.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-trending-down.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-bike.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-boat.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-caravan.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-jet-skiing.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-solar-eclipse.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/icon-truck.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/ic_baseline-business-center.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2025/05/bxs_bank.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/09/icon-blog-notes.svg
Blog
-
https://www.natloans.com.au/wp-content/uploads/2025/04/image-17-150x150.png
Picture of By Mary Nebotakis, Managing Director, Natloans, B. Eco, Dip. Financial Services
-
https://www.natloans.com.au/wp-content/uploads/2026/06/iStock-693956278.jpg
Mortgage Broker in Sandringham
-
https://www.natloans.com.au/wp-content/uploads/2026/04/NL0426-02_Awards_HORIZONTAL-scaled.png
(no alt text)
-
https://www.natloans.com.au/wp-content/uploads/2026/04/natloans-awards.png
(no alt text)